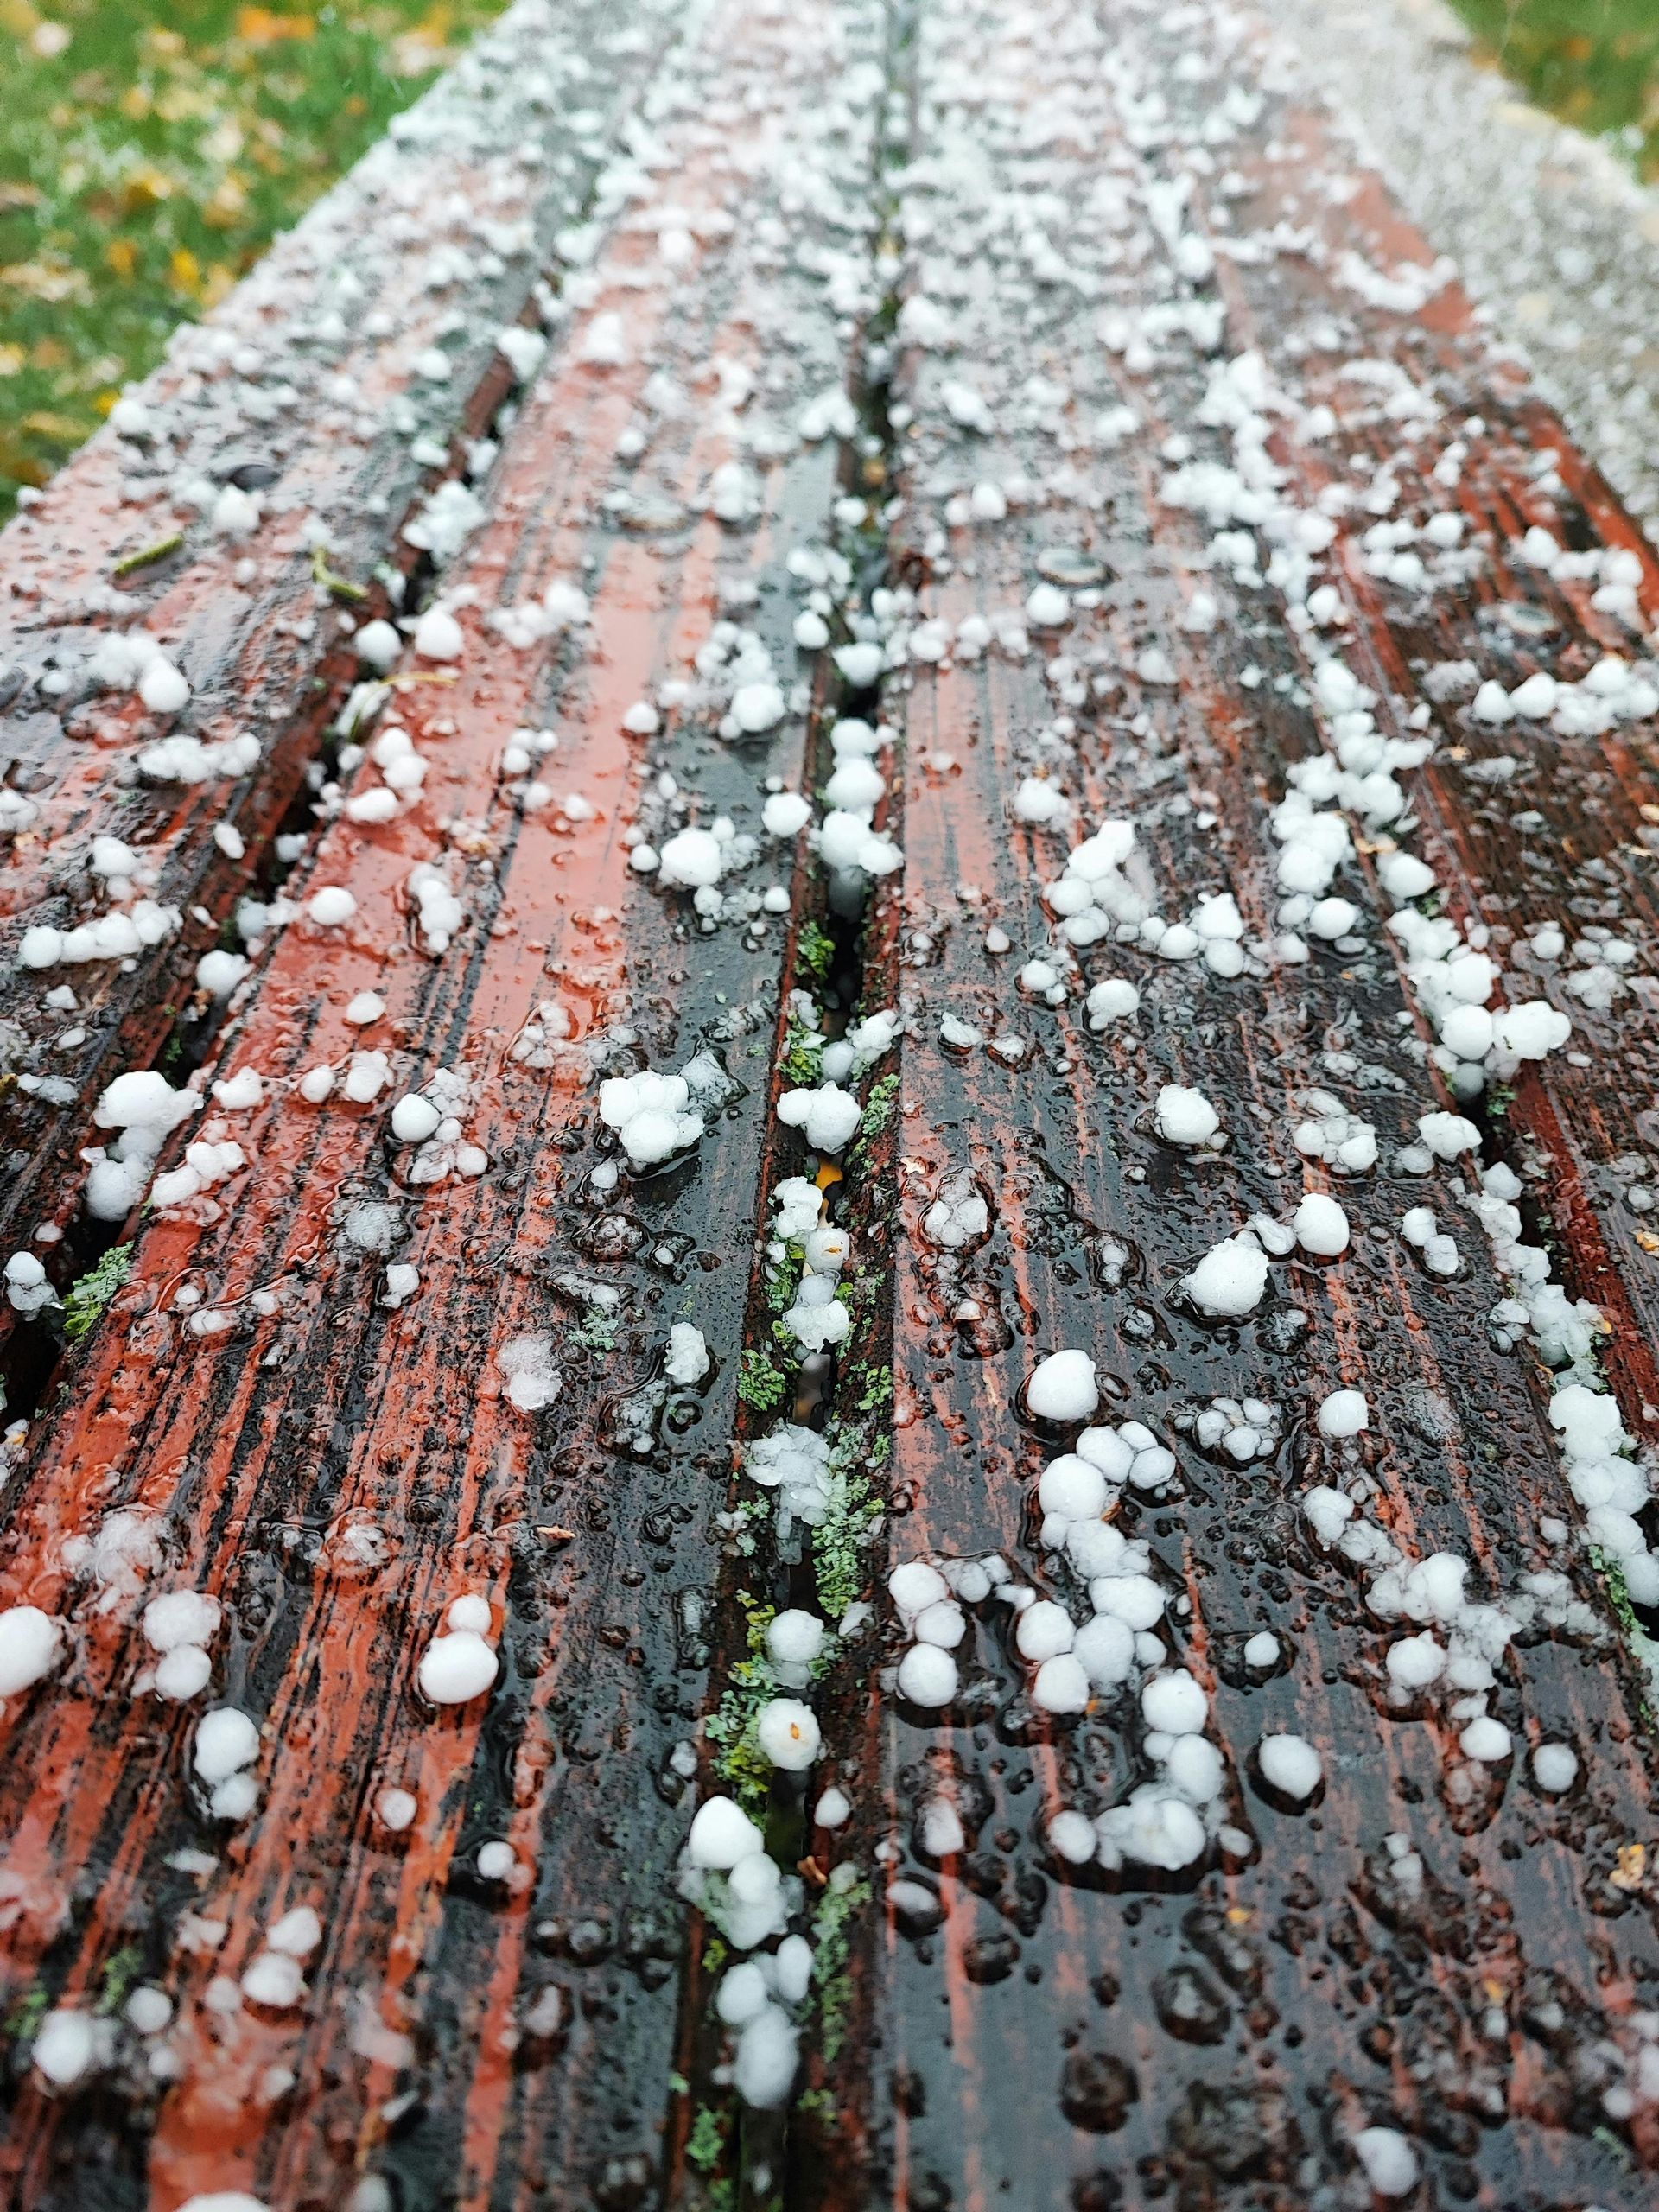
Texas leads the nation in hail damage claims, and if you own a home in the DFW metroplex, North Texas, or really anywhere in the state, it is not a matter of if you will deal with hail damage — it is when. Understanding how the claims process works before a storm hits can save you significant time, money, and frustration. At TAP Insurance Agency, we have extensive experience helping clients navigate insurance claims from start to finish. Here is what you need to know.
Step 1: Document the Damage Immediately
After a hail storm, take photos and videos of all visible damage to your roof, siding, windows, gutters, vehicles, and outdoor equipment. Do this as soon as it is safe, even before calling your insurance company. Time-stamped documentation strengthens your claim and provides a clear record of storm-related damage versus pre-existing wear. Walk around your entire property and look for dented gutters, cracked siding, broken window screens, and damage to outdoor furniture or structures.
Step 2: Contact Your Insurance Company Promptly
Most Texas homeowners policies require you to report damage promptly or within a reasonable time. Do not wait weeks or months to file. Call your insurance company or, better yet, call your insurance agent. At TAP Insurance, we help our clients file claims correctly and can communicate with the carrier on your behalf. When you call, have your policy number ready and be prepared to describe the damage in general terms.
Step 3: Understand the Adjuster's Role
Your insurance company will send an adjuster to inspect the damage. The adjuster works for the insurance company — their job is to assess the damage and determine the payout based on your policy terms. Be present during the inspection if possible, point out all areas of damage you have documented, and ask questions about anything you do not understand. If you believe the adjuster's assessment undervalues the damage, you have the right to get independent estimates and, if necessary, request a re-inspection or invoke the appraisal clause in your policy.
Step 4: Know Your Deductible
Many Texas homeowners policies include a separate wind and hail deductible, which is typically 1% or 2% of your home's insured value — not a flat dollar amount. For example, if your home is insured for $300,000 and you have a 2% wind/hail deductible, you will be responsible for the first $6,000 of damage before coverage kicks in. This surprises many homeowners who are accustomed to thinking about flat deductibles. Understanding your deductible before a storm helps you set realistic expectations about your out-of-pocket costs.
Common Mistakes to Avoid
Do not sign contracts with storm-chasing roofing companies that show up at your door immediately after a storm. While many roofers are legitimate, some pressure homeowners into signing agreements that limit your control over your own claim. Get multiple estimates and take your time. Do not accept the first settlement offer without reviewing it carefully. Review the adjuster report line by line. Do not make permanent repairs before the adjuster has inspected the damage. You can make temporary repairs like tarping a roof, but hold off on permanent work until the inspection is complete.
How TAP Insurance Helps With Hail Claims
At TAP Insurance Agency, we are your local advocate. Our team has real-world experience in claims and litigation management, and we help our clients understand their policy, communicate effectively with adjusters, and push for the full coverage they are entitled to. If you are not sure whether your current policy adequately covers hail damage, we can review it and recommend improvements before the next storm season.
Have questions about your hail damage coverage? Contact TAP Insurance Agency at (800) 666-2254 for a free policy review.