If you are an owner-operator leased onto a motor carrier in Texas, you have almost certainly heard two terms thrown around:
bobtail insurance and
non-trucking liability. They get used interchangeably all the time. They are not the same thing — and the gap between them is exactly the kind of detail that turns into an uncovered claim.
Here is a plain-English breakdown of what each coverage does, where they overlap, and how to make sure you are not driving around with a hole in your protection.
First — who actually needs these coverages?
Bobtail and non-trucking liability both exist for one specific situation: an
owner-operator who owns the truck but is leased onto a motor carrier's authority.
When you are leased on, the carrier provides the
primary liability coverage that protects you while you are dispatched — hauling a load, under their authority, doing their business. That primary policy is robust, but it has a hard boundary: it only covers you when you are working for the carrier.
The moment you are using the truck for something that is not dispatched business, that primary policy can stop responding. Bobtail and non-trucking liability are the two coverages built to fill that gap. If you run under your own authority, your own commercial auto liability policy is already covering you around the
clock and these add-ons usually do not apply the same way.
What is bobtail insurance?
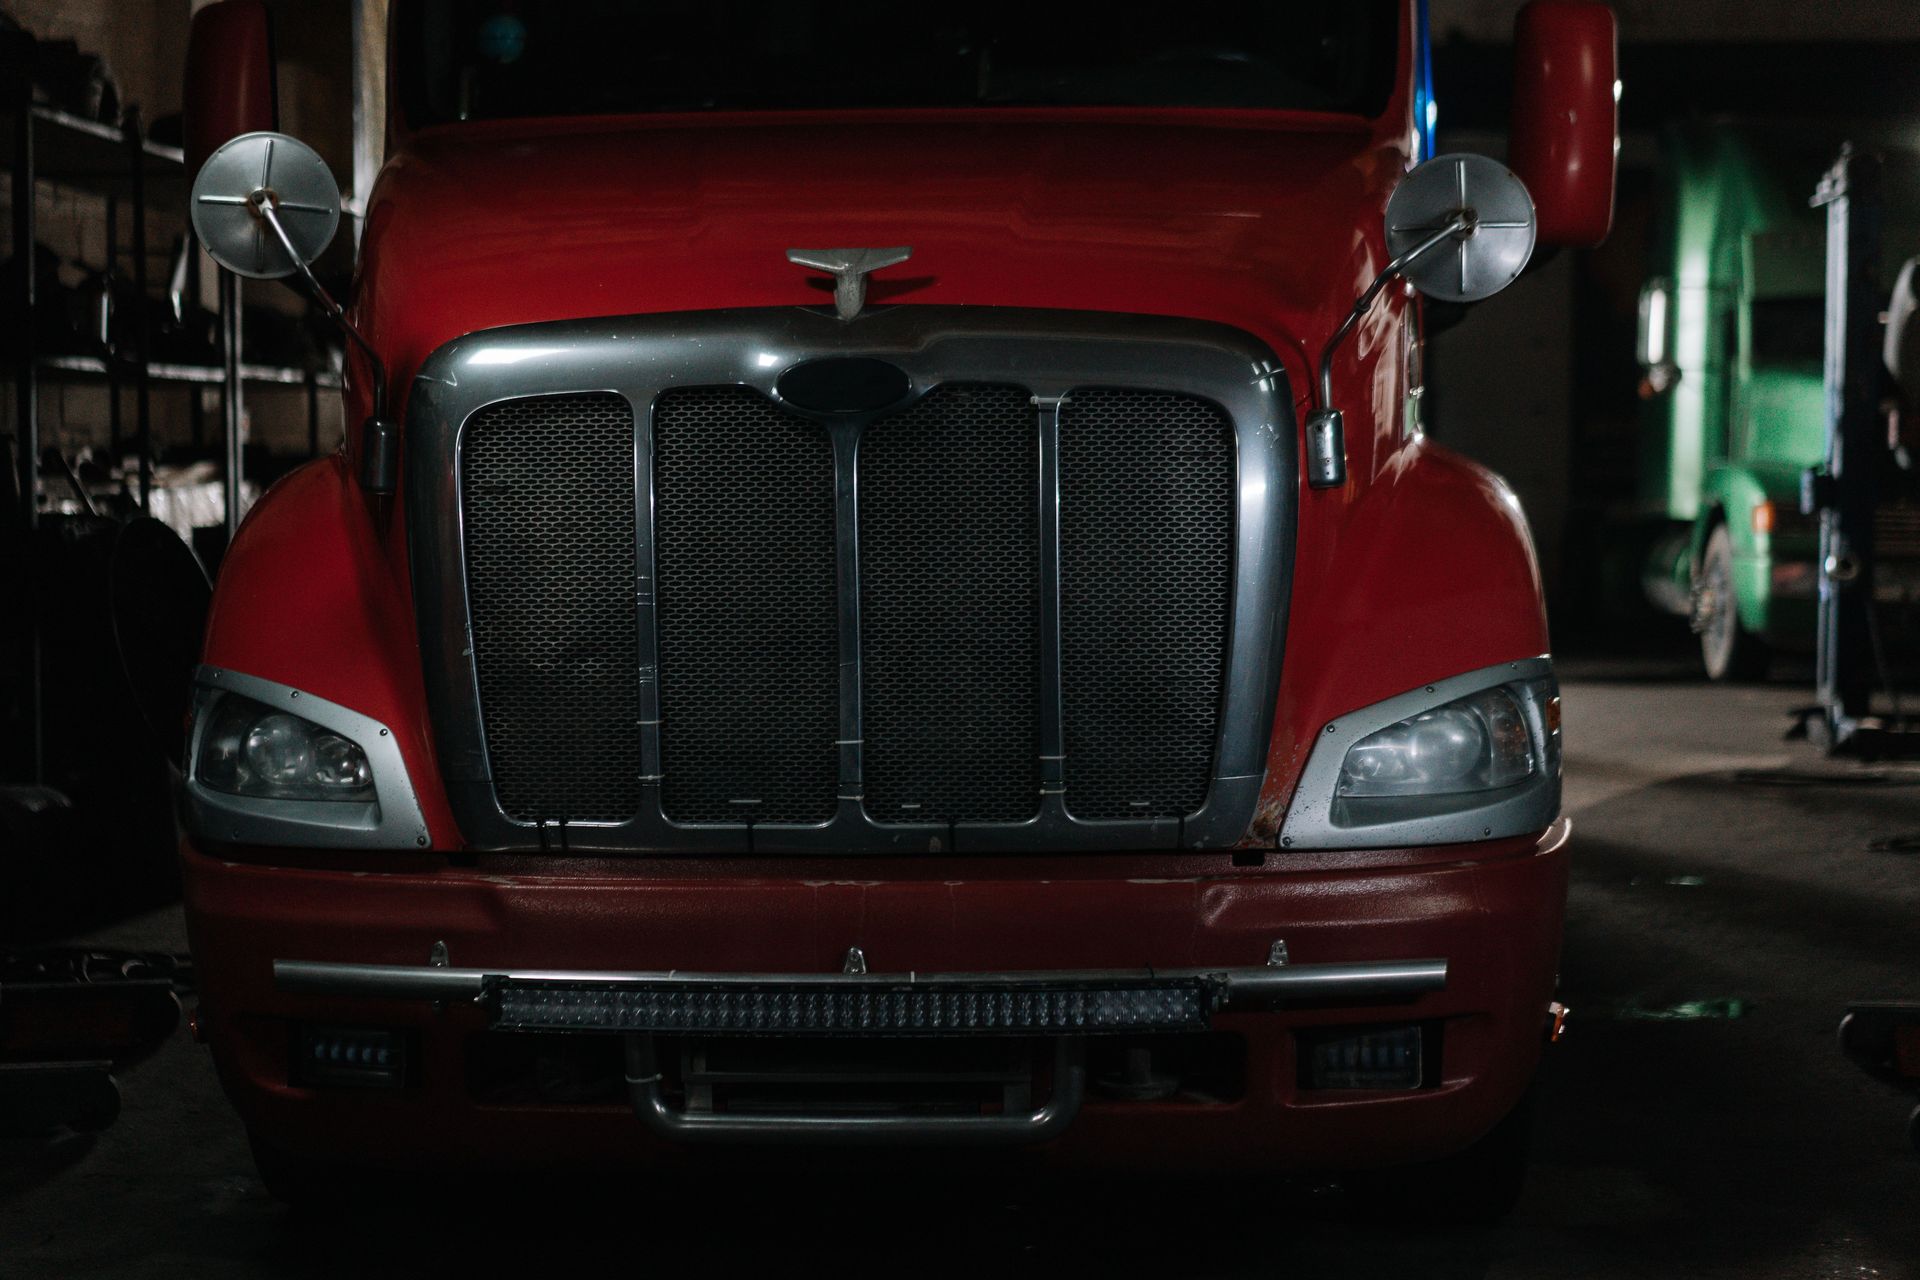
"Bobtailing" means driving the tractor
without a trailer attached. Picture dropping a loaded trailer at a receiver and driving the bare tractor back to the yard, or home.
Bobtail insurance provides liability coverage while you are operating the truck with no trailer connected — typically after you have completed a dispatch. If you cause an accident while bobtailing back from a delivery, this is the coverage that responds.
The key trigger is the physical configuration of the truck: no trailer. That is the classic, traditional definition, and it is why the coverage is sometimes called "bobtail liability."
What is non-trucking liability (NTL)?
Non-trucking liability is the broader and more commonly written of the two today. It covers the truck while you are using it for
personal, non-business use — when you are not under dispatch and not doing anything for the motor carrier.
The classic example is "bobtail to the house" — but NTL is about purpose, not configuration. Driving the truck to the grocery store, to a doctor's appointment, or on a personal errand on your day off is non-trucking use, whether or not a trailer happens to be attached.
That is the cleaner way to think about it: bobtail is defined by no trailer; non-trucking liability is defined by not working.
Bobtail vs. NTL — the real difference
Here is the difference in one line.
Bobtail coverage is keyed to whether a trailer is attached.
Non-trucking liability is keyed to whether you are doing business for the carrier.
In practice, most modern policies are written as non-trucking liability because it answers the question that actually matters in a claim — "were you working or not?" — rather than the narrower "was a trailer attached?" Many people in the industry still say "bobtail" out of habit when they really mean NTL.
What this means for you is simple but important: do not assume. When you buy this coverage, confirm in writing exactly what triggers it. A policy that only responds when you are trailer-free is narrower than one that responds whenever you are off-dispatch.
What neither coverage does
This is the part that prevents nasty surprises. Bobtail and non-trucking liability are
liability-only coverages for off-dispatch driving. They do not do several things owner-operators often assume they do.
They do not cover damage to your own truck. That is physical damage coverage — collision and comprehensive — and it is a separate purchase.
They do not cover you while you are under dispatch. That is the carrier's primary liability.
They do not cover the freight. That is motor truck cargo insurance. And
they do not replace your own operating authority's commercial auto policy if you run independently.
NTL is a narrow, specific tool. It plugs one gap — the off-duty gap — and it does that job well. It is not a full insurance program on its own.
Getting your owner-operator coverage right
The cleanest way to avoid gaps is to look at your whole setup at once: the carrier's primary liability, your non-trucking liability, physical damage on the truck, and — if you ever haul under your own authority — full commercial auto. The pieces have to fit together without overlaps you are paying twice for or gaps no one is covering.
That is the value of working with an independent agency. TAP Insurance Agency shops multiple trucking markets, reads your lease agreement to see exactly what the carrier does and does not provide, and builds the rest of your coverage around it. If you are newer to running your own truck, our guide to the
five things every new owner-operator needs to know about insurance is a good starting point, and our
owner-operator insurance overview lays out the full picture. Business owners whose employees drive personal vehicles for work should also look at
hired and non-owned auto insurance, which solves a related but separate problem.
If you are not sure whether your bobtail or non-trucking coverage actually does what you think it does, let us take a look. The review is free and there is no pressure to switch.
Call us at (800) 666-2254 or request a free quote at
tapinsuretx.com.