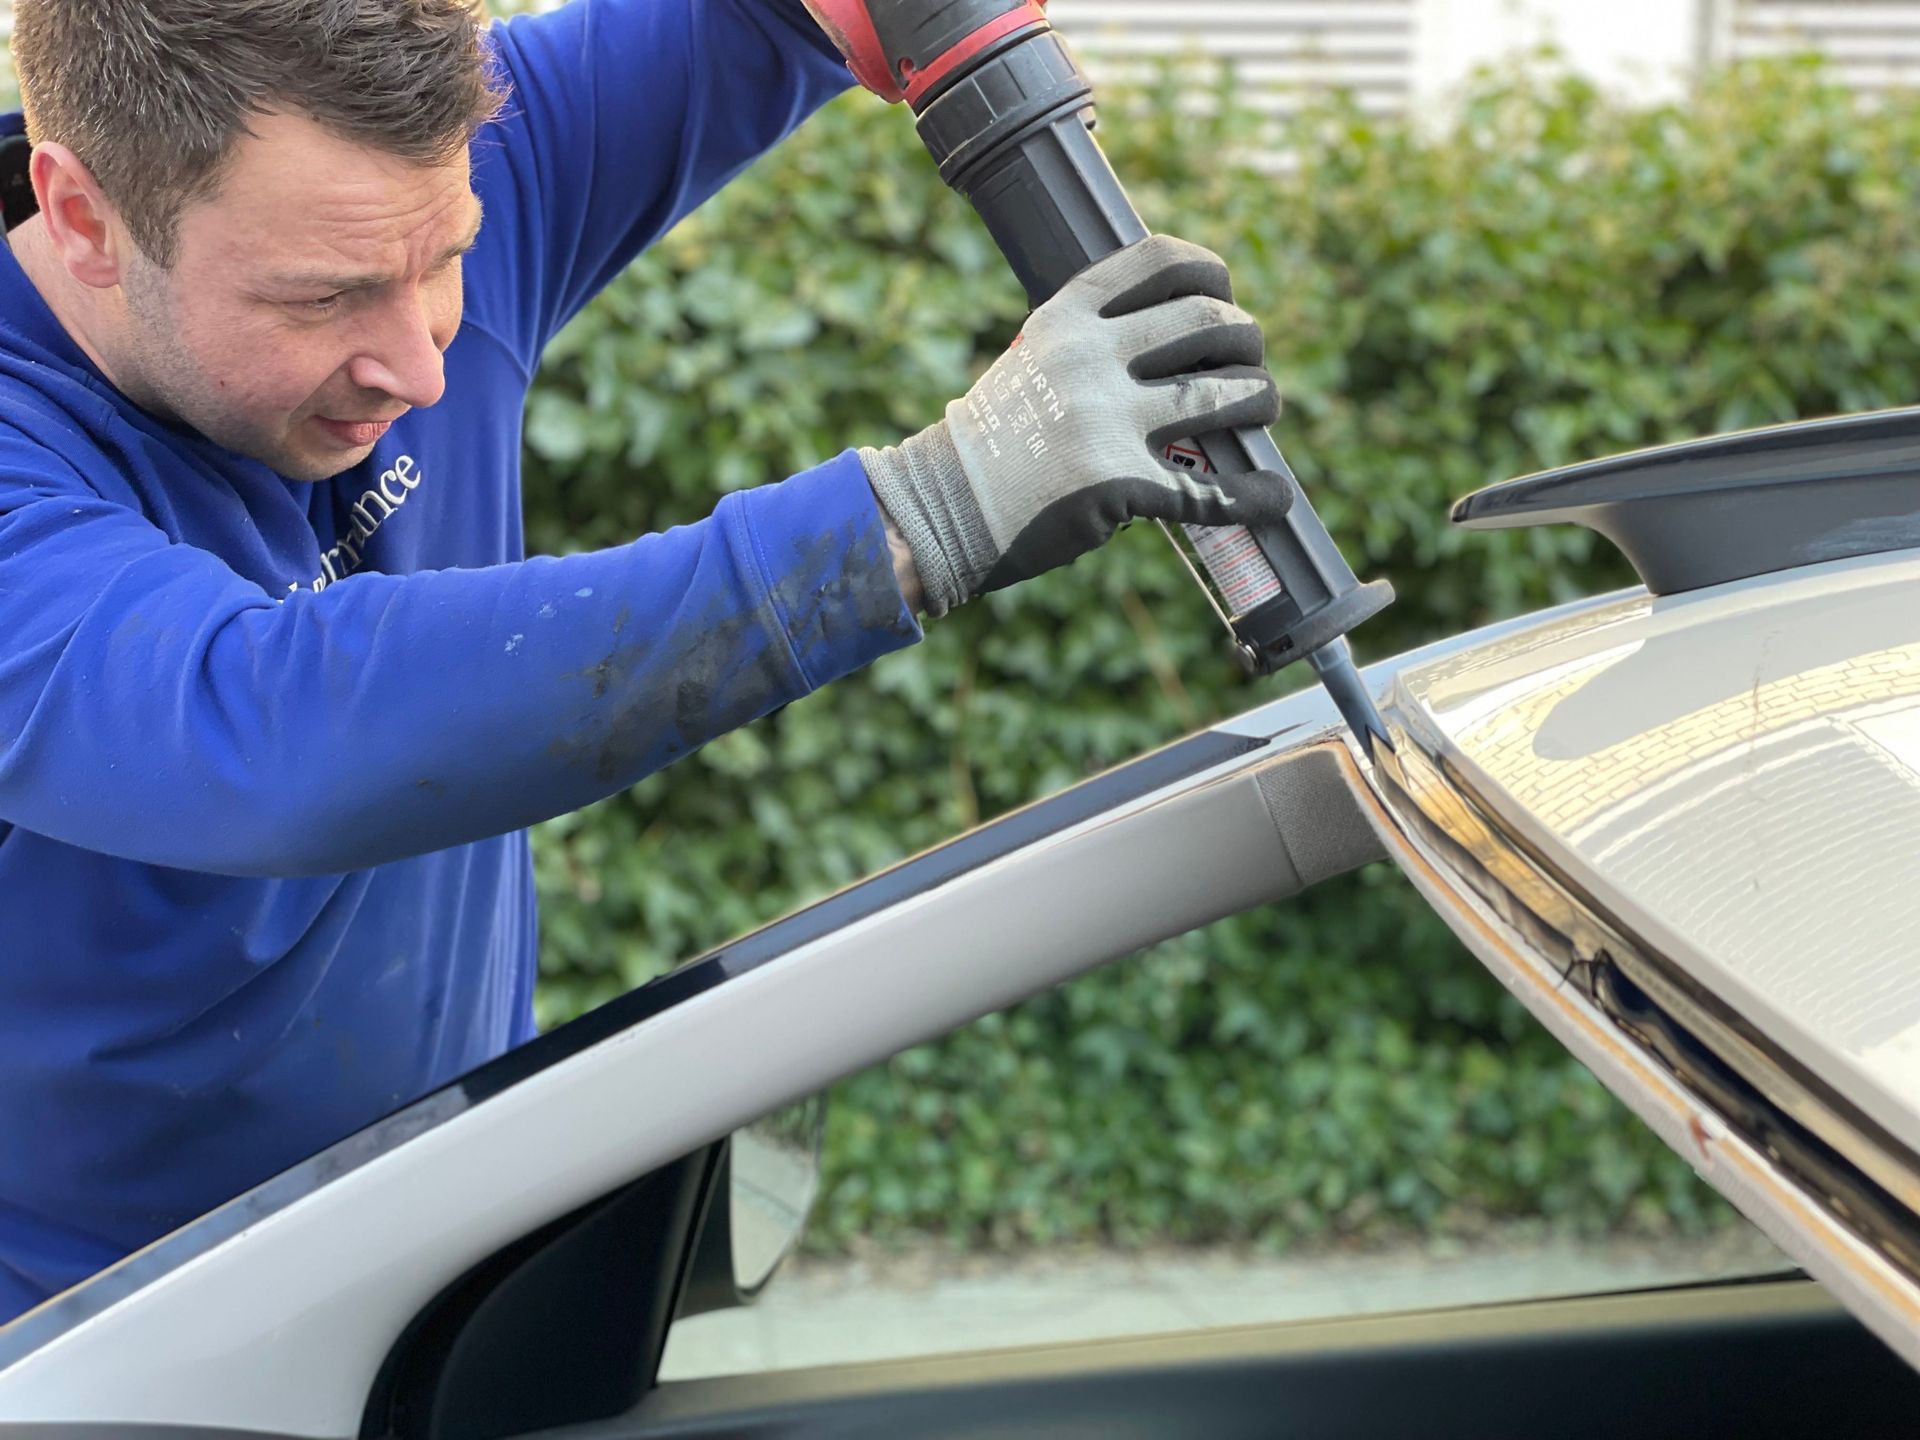
Say a driver spends her days on the FM roads around Bridgeport hauling feed for her cattle, and a rock kicked loose by a passing truck stars her windshield on an ordinary Tuesday morning on her way back from the feed store. She calls her agent expecting the usual: file a comprehensive claim, get a new windshield, done. What she doesn't expect is being told she still owes her regular comprehensive deductible first, because nobody had ever added the one coverage that would have waived it for exactly this kind of claim.
Standard comprehensive coverage already pays for a cracked or shattered windshield, but it applies your ordinary comprehensive deductible the same way it would for hail damage or a stolen stereo. A $0-deductible windshield replacement is not automatic in Texas. It only happens when a driver has specifically added full glass coverage, a separate endorsement built to waive the deductible for glass claims and glass claims alone.
That distinction is easy to miss because the two coverages sound like they should be the same thing. Comprehensive is the broad coverage that responds to non-collision damage of almost any kind, and it already includes glass. Full glass coverage doesn't add new protection on top of that; it narrows in on one specific claim type and removes the deductible from it.
Why Texas doesn't guarantee a $0-deductible windshield
A handful of states require insurers to waive the glass deductible by law, and drivers who move to Texas from one of those states sometimes assume the rule follows them. Texas has no statewide law mandating a $0 glass deductible. Whether a windshield claim costs a driver anything out of pocket here depends entirely on whether full glass coverage, sometimes called safety glass coverage, was added to the policy.
That gap in expectations matters most because of a related mix-up drivers make: knowing
the difference between full coverage and liability-only doesn't automatically tell you whether glass has its own deductible waiver. A driver can carry robust comprehensive protection, the kind that already covers hail, theft, and collision, and still owe a deductible on a cracked windshield if the glass endorsement was never part of the conversation.
What the glass endorsement actually waives
Full glass coverage is a policy add-on, not a separate policy, and it works alongside comprehensive rather than replacing it. Once it's in place, a covered windshield claim, whether it's a full replacement or in many cases a chip repair, is handled without the driver paying the deductible that would otherwise apply.
Comprehensive coverage alone. Pays for a windshield claim, but the claim is subject to your regular comprehensive deductible, the same amount that applies to hail or theft.
Comprehensive plus full glass coverage. Pays for a windshield claim with the deductible waived specifically for glass, while every other comprehensive claim still carries your normal deductible.
Some insurers will waive the deductible on a windshield repair, as opposed to a full replacement, even without the glass endorsement in place, since a small chip repaired early is cheaper for everyone than a full pane replaced later. That's a separate, narrower practice from full glass coverage, and it isn't something to count on without asking your specific carrier how it actually handles repairs versus replacements.
How a claim without the endorsement actually plays out
Without full glass coverage, a windshield claim still runs through the ordinary comprehensive process: the insurer determines the repair or replacement cost using the same logic behind
how a comprehensive claim gets valued on a larger loss, and the driver pays the comprehensive deductible before the insurer covers the rest.
That's not a penalty or a denial. It's simply comprehensive coverage working exactly as designed, without the one add-on that would have zeroed out the driver's share of a glass claim specifically. The coverage was always there; the deductible just wasn't waived.
Who a cracked windshield actually costs the most
A windshield claim isn't rare in Texas. Rock chips from gravel roads, farm-to-market highways, and construction zones are common enough that most drivers here will face one eventually, and how much that costs out of pocket depends heavily on how someone actually drives.
Heavy gravel or FM-road commuters. A driver who spends real time behind trucks, trailers, or loose gravel on rural roads faces meaningfully higher odds of a rock chip or crack than a driver who mostly stays on paved city streets, which makes the deductible waiver worth more relative to what it costs to add.
Mostly in-town drivers. A driver who rarely leaves paved surfaces and light traffic faces lower odds of a glass claim in any given year, so the math on adding the endorsement looks different, though a single unlucky chip on a highway trip is still enough to make it worth a second look.
Neither situation makes full glass coverage mandatory. It's an optional add-on either way, and the right call depends on how often a windshield is actually exposed to the kind of debris that cracks one, not on some statewide default that does the deciding for you.
The practical step: ask for it by name
Full glass coverage is not automatically included with comprehensive, and it usually isn't offered up front unless a driver asks. The one reliable way to know whether it's on a policy is to ask an agent directly, using the term "full glass coverage" or "safety glass coverage" by name, rather than assuming comprehensive already includes it.
That question is worth asking at every renewal, not just when a policy is first written, since coverage details can shift between carriers and even between renewal terms with the same carrier. A five-minute call is a lot cheaper than finding out the answer mid-claim, on the side of an FM road with a starred windshield and a deductible you didn't budget for.
If it's been a while since anyone actually reviewed what your policy includes,
a full auto insurance review is the simplest way to find out where a glass endorsement, or any other gap, might be sitting unnoticed.
Call
(800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.