

Is Your Roof on an ACV Schedule? A North Texas Hail Coverage Guide

Nate Mclaughlin • June 16, 2026

When your roof ages, your hail coverage can quietly change. Here is how to check before the next North Texas storm.

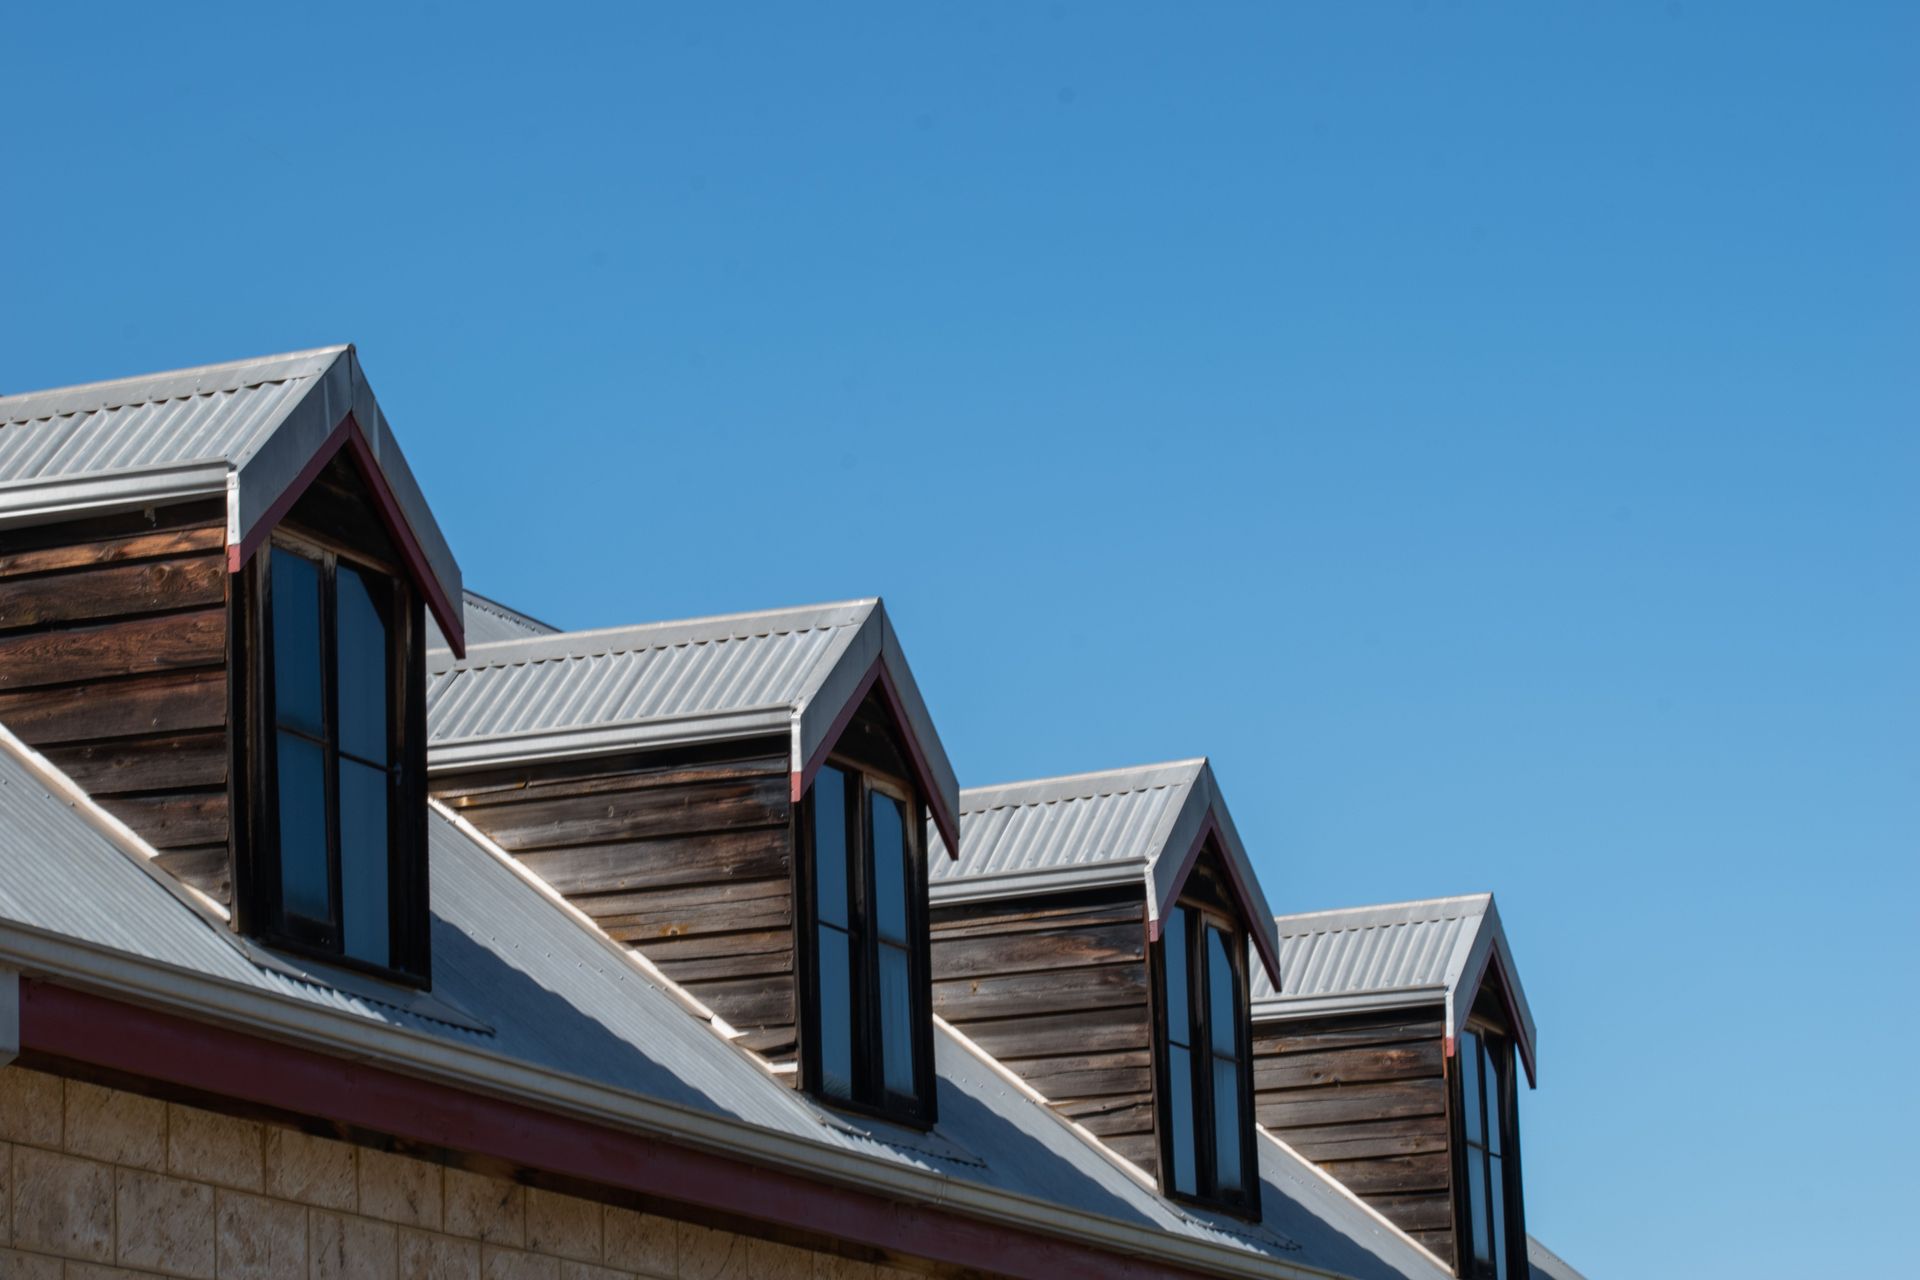
Row of dormer windows on a sloped roof against a clear blue sky

When a hailstorm rolls through North Texas — and in places like Rhome, Decatur, and the rest of Wise County, it is a "when," not an "if" — the biggest factor in how much money comes out of your pocket is not your deductible. It is a small clause that tells your insurer how to pay for your roof. It is called your roof settlement schedule, and it has quietly become one of the most important lines in any Texas home policy.

ACV vs. RCV: The Difference That Costs Thousands

There are two ways an insurer can pay a roof claim. Replacement Cost Value (RCV) pays what it actually costs to put a new roof on your home today, minus your deductible. Actual Cash Value (ACV) pays the depreciated value of your old roof — its worth after years of sun, age, and wear are subtracted.

Here is why that matters. Say a new roof costs $18,000 and your roof is 12 years old. On an RCV policy, you would recover roughly $18,000 minus your deductible. On an ACV policy, the insurer might depreciate that roof by 50% or more — leaving you a check for $9,000 or less, with the rest of the bill landing on you.

Why More North Texas Roofs Are Landing on ACV

For years, RCV was the default. That has changed fast. After a string of expensive hail seasons, many carriers writing in DFW and the surrounding counties have shifted older roofs onto ACV roof payment schedules — sometimes automatically once a roof passes 10, 15, or 20 years of age. The catch is that most homeowners never notice. The change shows up in a multi-page renewal packet, not a phone call. You find out after the storm, when the adjuster's check is far smaller than you expected.

How to Check Your Own Policy Today

You do not have to wait for a claim to find out where you stand. Pull out your declarations page and look for:

  • "Roof Surfacing — Actual Cash Value" or an "ACV roof" endorsement
  • A "roof payment schedule" or "roof depreciation schedule" table
  • Wind and hail deductibles listed as a percentage (1%, 2%) rather than a flat dollar amount

If you see any of these and do not fully understand them, that is exactly the kind of thing worth a five-minute conversation before the next storm — not after.

What You Can Do About It

  • Ask whether RCV roof coverage is still available for your home, and what it costs.
  • If your roof is newer, make sure you are getting credit for it.
  • Consider a wind and hail deductible buy-down or a standalone deductible reimbursement product to soften a percentage-based deductible.
  • Document your roof's age and condition now, while it is in good shape.

As an independent agency, TAP Insurance can shop your home across multiple carriers and compare not just the premium, but how each one would actually pay a roof claim. Two policies that look identical on price can be thousands of dollars apart when the hail hits.

Do not let a buried clause decide what your roof is worth. Call TAP Insurance at (800) 666-2254 or visit tapinsuretx.com for a free policy review and quote — and head into storm season knowing exactly where you stand.


A pen resting on a signature line, the page where a business owner agrees to repay a surety
By Nate Mclaughlin • November 4, 2026
A claim was filed against your surety bond. What the indemnity agreement says you owe, how a bond claim moves and what to do the day the surety's letter arrives.

A worn hitch ball on a vehicle's rear bumper, the point where a trailer hooks on as its own unit
By Nate Mclaughlin • November 3, 2026
Is your gooseneck covered if hail hits it or it is stolen from the yard? How owned trailers are scheduled, valued and covered on a Texas hotshot policy.

A building inspector with a clipboard, the code review that can change what a rebuild must include
By Nate Mclaughlin • November 3, 2026
Who pays when a city requires code upgrades after a fire or storm? How ordinance or law coverage works for Texas commercial buildings, in its three parts.

Two workers in hard hats, safety glasses and orange vests, the crew safety behind a claim history
By Nate Mclaughlin • November 2, 2026
Why did your workers' comp renewal go up? How a Texas experience modification factor is built from your claims, who has one, and what moves the number.

A dog looking through an iron yard gate, the family pet whose breed and bite history shape a claim
By Nate Mclaughlin • November 1, 2026
A dog bites a guest or a neighbor. What Texas homeowners liability coverage pays, how breed exclusions and bite history change it, and when limits run short.

A smoke detector on a ceiling, the small device between a close call and months away from home
By Nate Mclaughlin • October 31, 2026
If a fire or storm makes your Texas home unlivable, additional living expense pays the extra costs. What it covers, how long it lasts and how to claim it.

A bartender pouring a drink at a bar, the point where a host starts answering for a guest's night
By Nate Mclaughlin • October 30, 2026
Hosting a holiday party or serving drinks at your business? How host liquor and liquor liability coverage differ for Texas businesses, and what to check first.

Pallets of boxed freight stacked in a warehouse, a load that depends on reaching the right door
By Nate Mclaughlin • October 29, 2026
A driver delivers to a fake receiver. Does cargo coverage pay? How voluntary parting and fraud exclusions work for Texas carriers heading into holiday freight.

A plumber tightening a pipe fitting under a sink, finished work that can fail long after it is paid
By Nate Mclaughlin • October 29, 2026
A finished job can still bring a lawsuit. How completed operations coverage works for Texas contractors, what takes it away, and what to check before you switch.

A white hard hat beside a clipboard and building plans, the paperwork a contractor needs from a sub
By Nate Mclaughlin • October 28, 2026
Hiring a sub without a certificate can raise your GL and comp audit and leave you holding the claim. How Texas contractors vet subs before the first check.
Show More