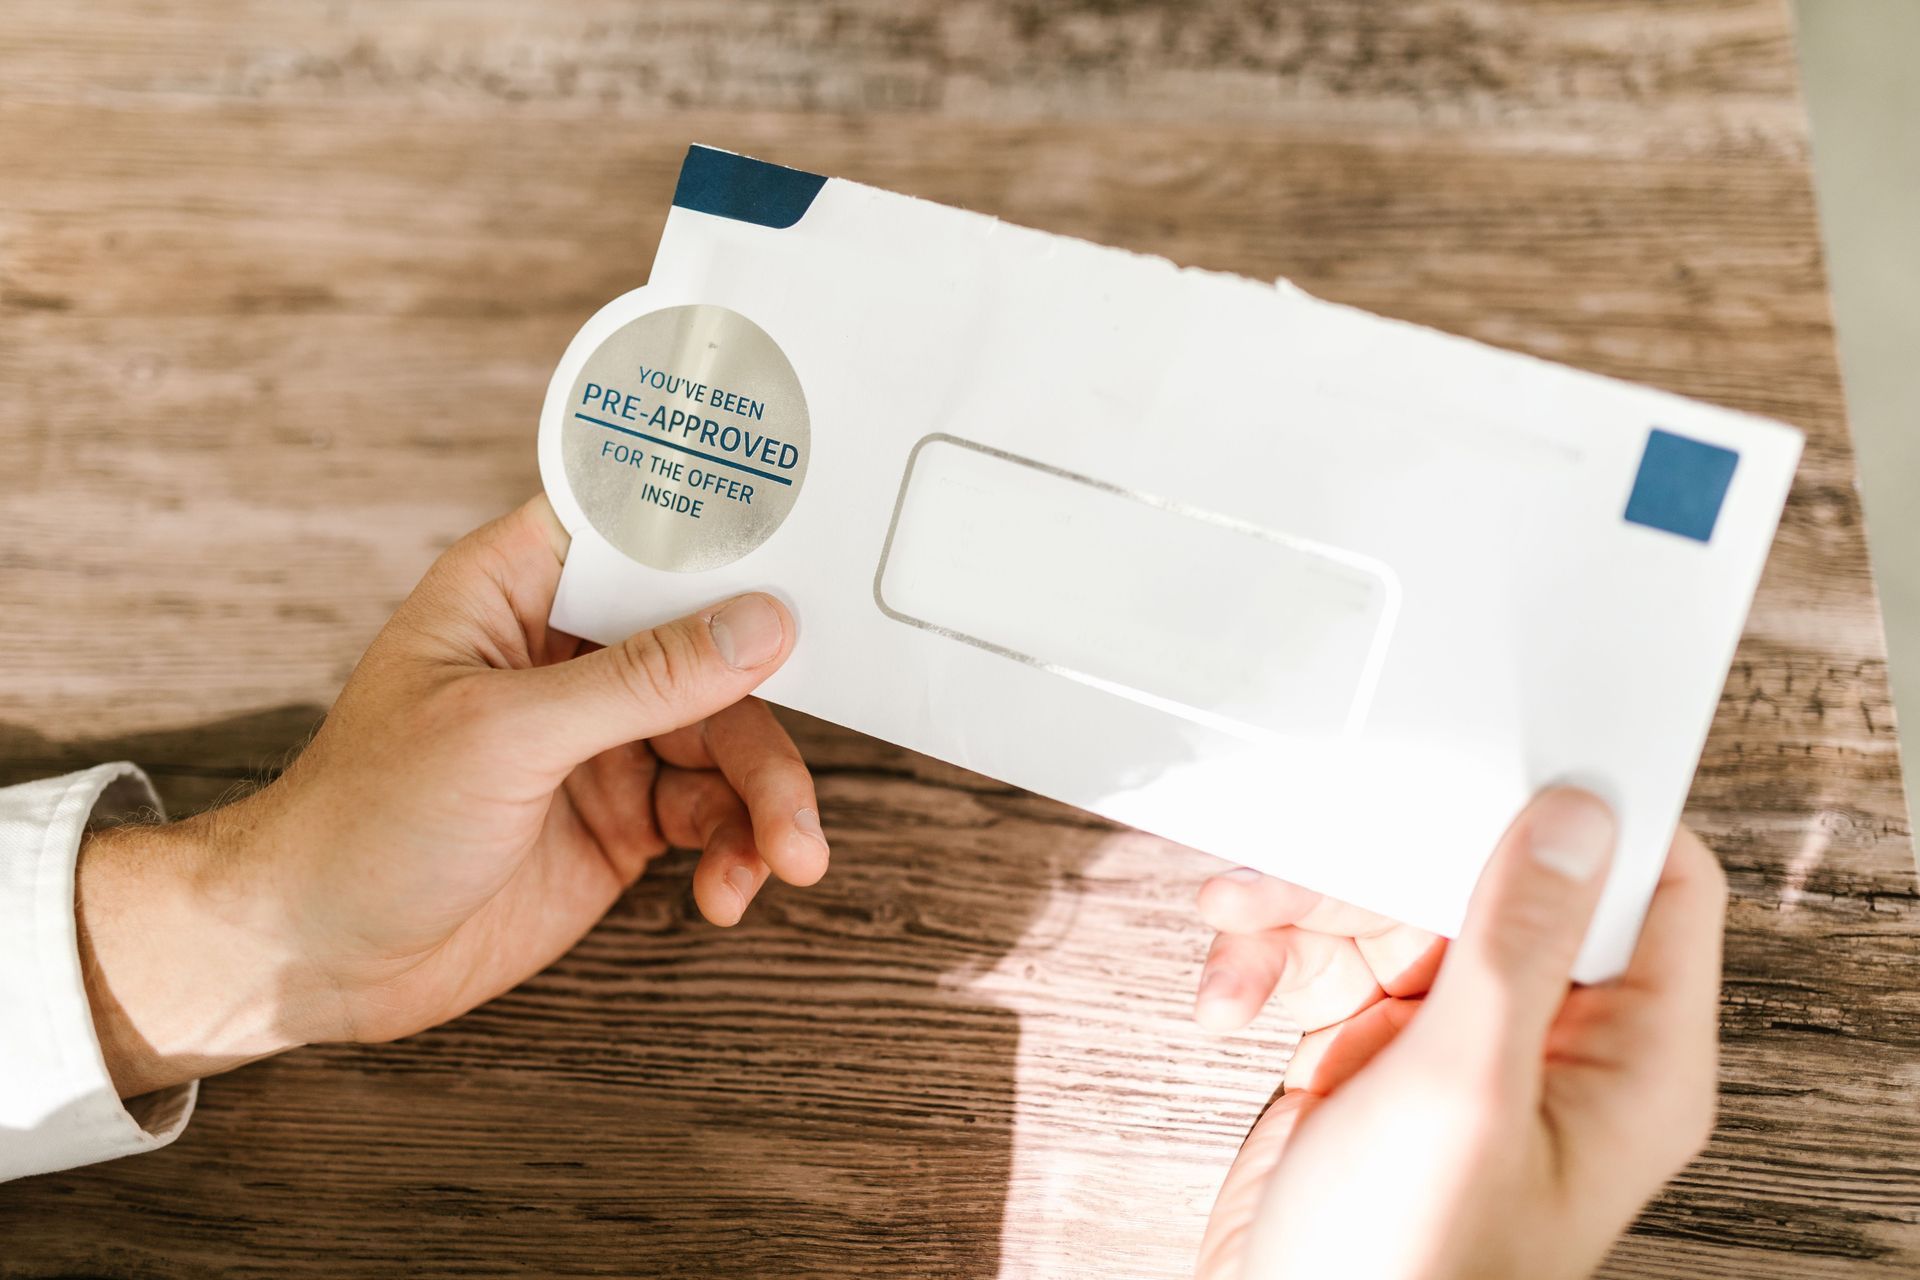
Picture a young couple who closed on a house outside Bridgeport in September. A week later, the mailbox fills with envelopes that use their loan amount and the name of the street. Each one says the same thing in different words: if something happens to you, this pays off your mortgage. It feels responsible, it feels personalized, and it is easy to say yes to before anyone has compared it with anything.
Here is the plain answer. Mortgage protection insurance is a life insurance product marketed around your home loan. Term life insurance pays a death benefit to a beneficiary you choose, and that person can use it for the mortgage, the kids, or anything else. The real decision is not the name on the envelope but how much coverage you need, for how long, and who gets the money.
Three products with similar names
Mortgage protection. Sold around your loan, often through direct mail and sometimes with simplified underwriting. The coverage amount is commonly tied to the mortgage balance, and some versions reduce as the loan is paid down. Features vary widely by carrier, so read who the beneficiary is and how the benefit is paid.
Term life. A policy for a set period, such as 20 or 30 years, that pays a beneficiary you name. It is not tied to any loan, the amount usually stays level, and the family decides how to use the money. That flexibility is why many households prefer it.
Credit life. Sometimes offered by the lender at closing. It pays the lender directly to retire the debt, so your family gets a paid-off house but no cash. The coverage amount falls as the balance falls, while the price often does not.
One more name is worth clearing up, since it causes confusion. Private mortgage insurance, or PMI, protects the lender if you stop paying. It does not protect your family and has nothing to do with life insurance.
Whichever product you compare, the beneficiary designation is where the money goes, and it is worth getting right. We covered the beneficiary mistakes that cost families
real money in a separate post, and it is a good ten-minute read before you fill out any form.
Where the two approaches differ in practice
Who gets the money. With term life, your beneficiary chooses. If a surviving spouse would rather keep a low-rate mortgage and use cash for the kids' costs, they can. With a policy that pays the lender, that choice disappears. This is also why the beneficiary form matters so much.
How much coverage. A mortgage is one bill among many. A household that loses an income still has groceries, insurance, car payments, childcare and college to pay for. Coverage that matches only the loan balance can leave those needs unmet.
How the benefit changes over time. A decreasing benefit makes sense for the loan, since the balance is falling, but your family's other needs do not shrink at the same rate.
Underwriting. Simplified-issue products can be convenient if health is a concern, but convenience is sometimes priced into them. Ask for a comparison with fully underwritten term life, since a healthy applicant often does better there.
How to size the coverage
Start with the mortgage balance, then add the income your family would need to replace and for how many years. Add other debts and a rough figure for future costs like college. Subtract savings and any coverage you already have through work. Your agent can help with the math, and the answer is usually bigger than the loan.
Households with one earner and one caregiver should count both. If a parent stays home, replacing childcare and household work is a real cost, which we covered in our post on life insurance for
a stay-at-home parent.
What moves the price
Price depends on your age, health, tobacco use, the amount of coverage, and the length of the term. A longer term or a larger amount costs more, and a healthy applicant usually gets a better rating. Riders that add features also add cost. Rather than chase the lowest number, compare what each policy does and who it pays.
What to do with the mail you already received
Do not respond to the first letter. Keep the envelopes and the sales material, since the fine print explains who the beneficiary is and how the benefit is paid. Many life policies include a free-look period after delivery that allows you to cancel for a refund, and asking about it is a fair question before you commit.
Take the mailers to an agent and ask for a side-by-side comparison with a term policy for the same amount. Seeing them next to each other is the fastest way to tell whether the convenience is worth the difference.
When mortgage protection can still make sense
It is not a bad product for everyone. A buyer with health conditions that make standard underwriting hard may find simplified issue is the way to get coverage at all. A buyer who wants the mortgage paid off no matter what, and does not need more, may be happy with the simplicity. The point is to choose it with a comparison in hand, not because the letter had your address on it.
There is a middle path too. Some households buy a term policy sized for the whole picture, mortgage included, and then add a small simplified policy only if health limits their options. The right answer depends on the household, and an honest comparison is the only way to see it. Whatever you choose, revisit it after a refinance, a new child, or a big change in income.
Questions to ask before you sign anything
Who is the beneficiary, and can it be changed? Does the benefit decrease? Is the premium level? Is there a health questionnaire, and does the policy have a waiting period? What happens if you refinance or sell the house? A policy tied to one loan may not follow you to the next.
If you would like to compare options side by side, ask for
a life insurance quote from an independent agency that can look at multiple carriers, and bring the mailers you received. We are happy to explain what each one does and does not do.
Call
(800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.