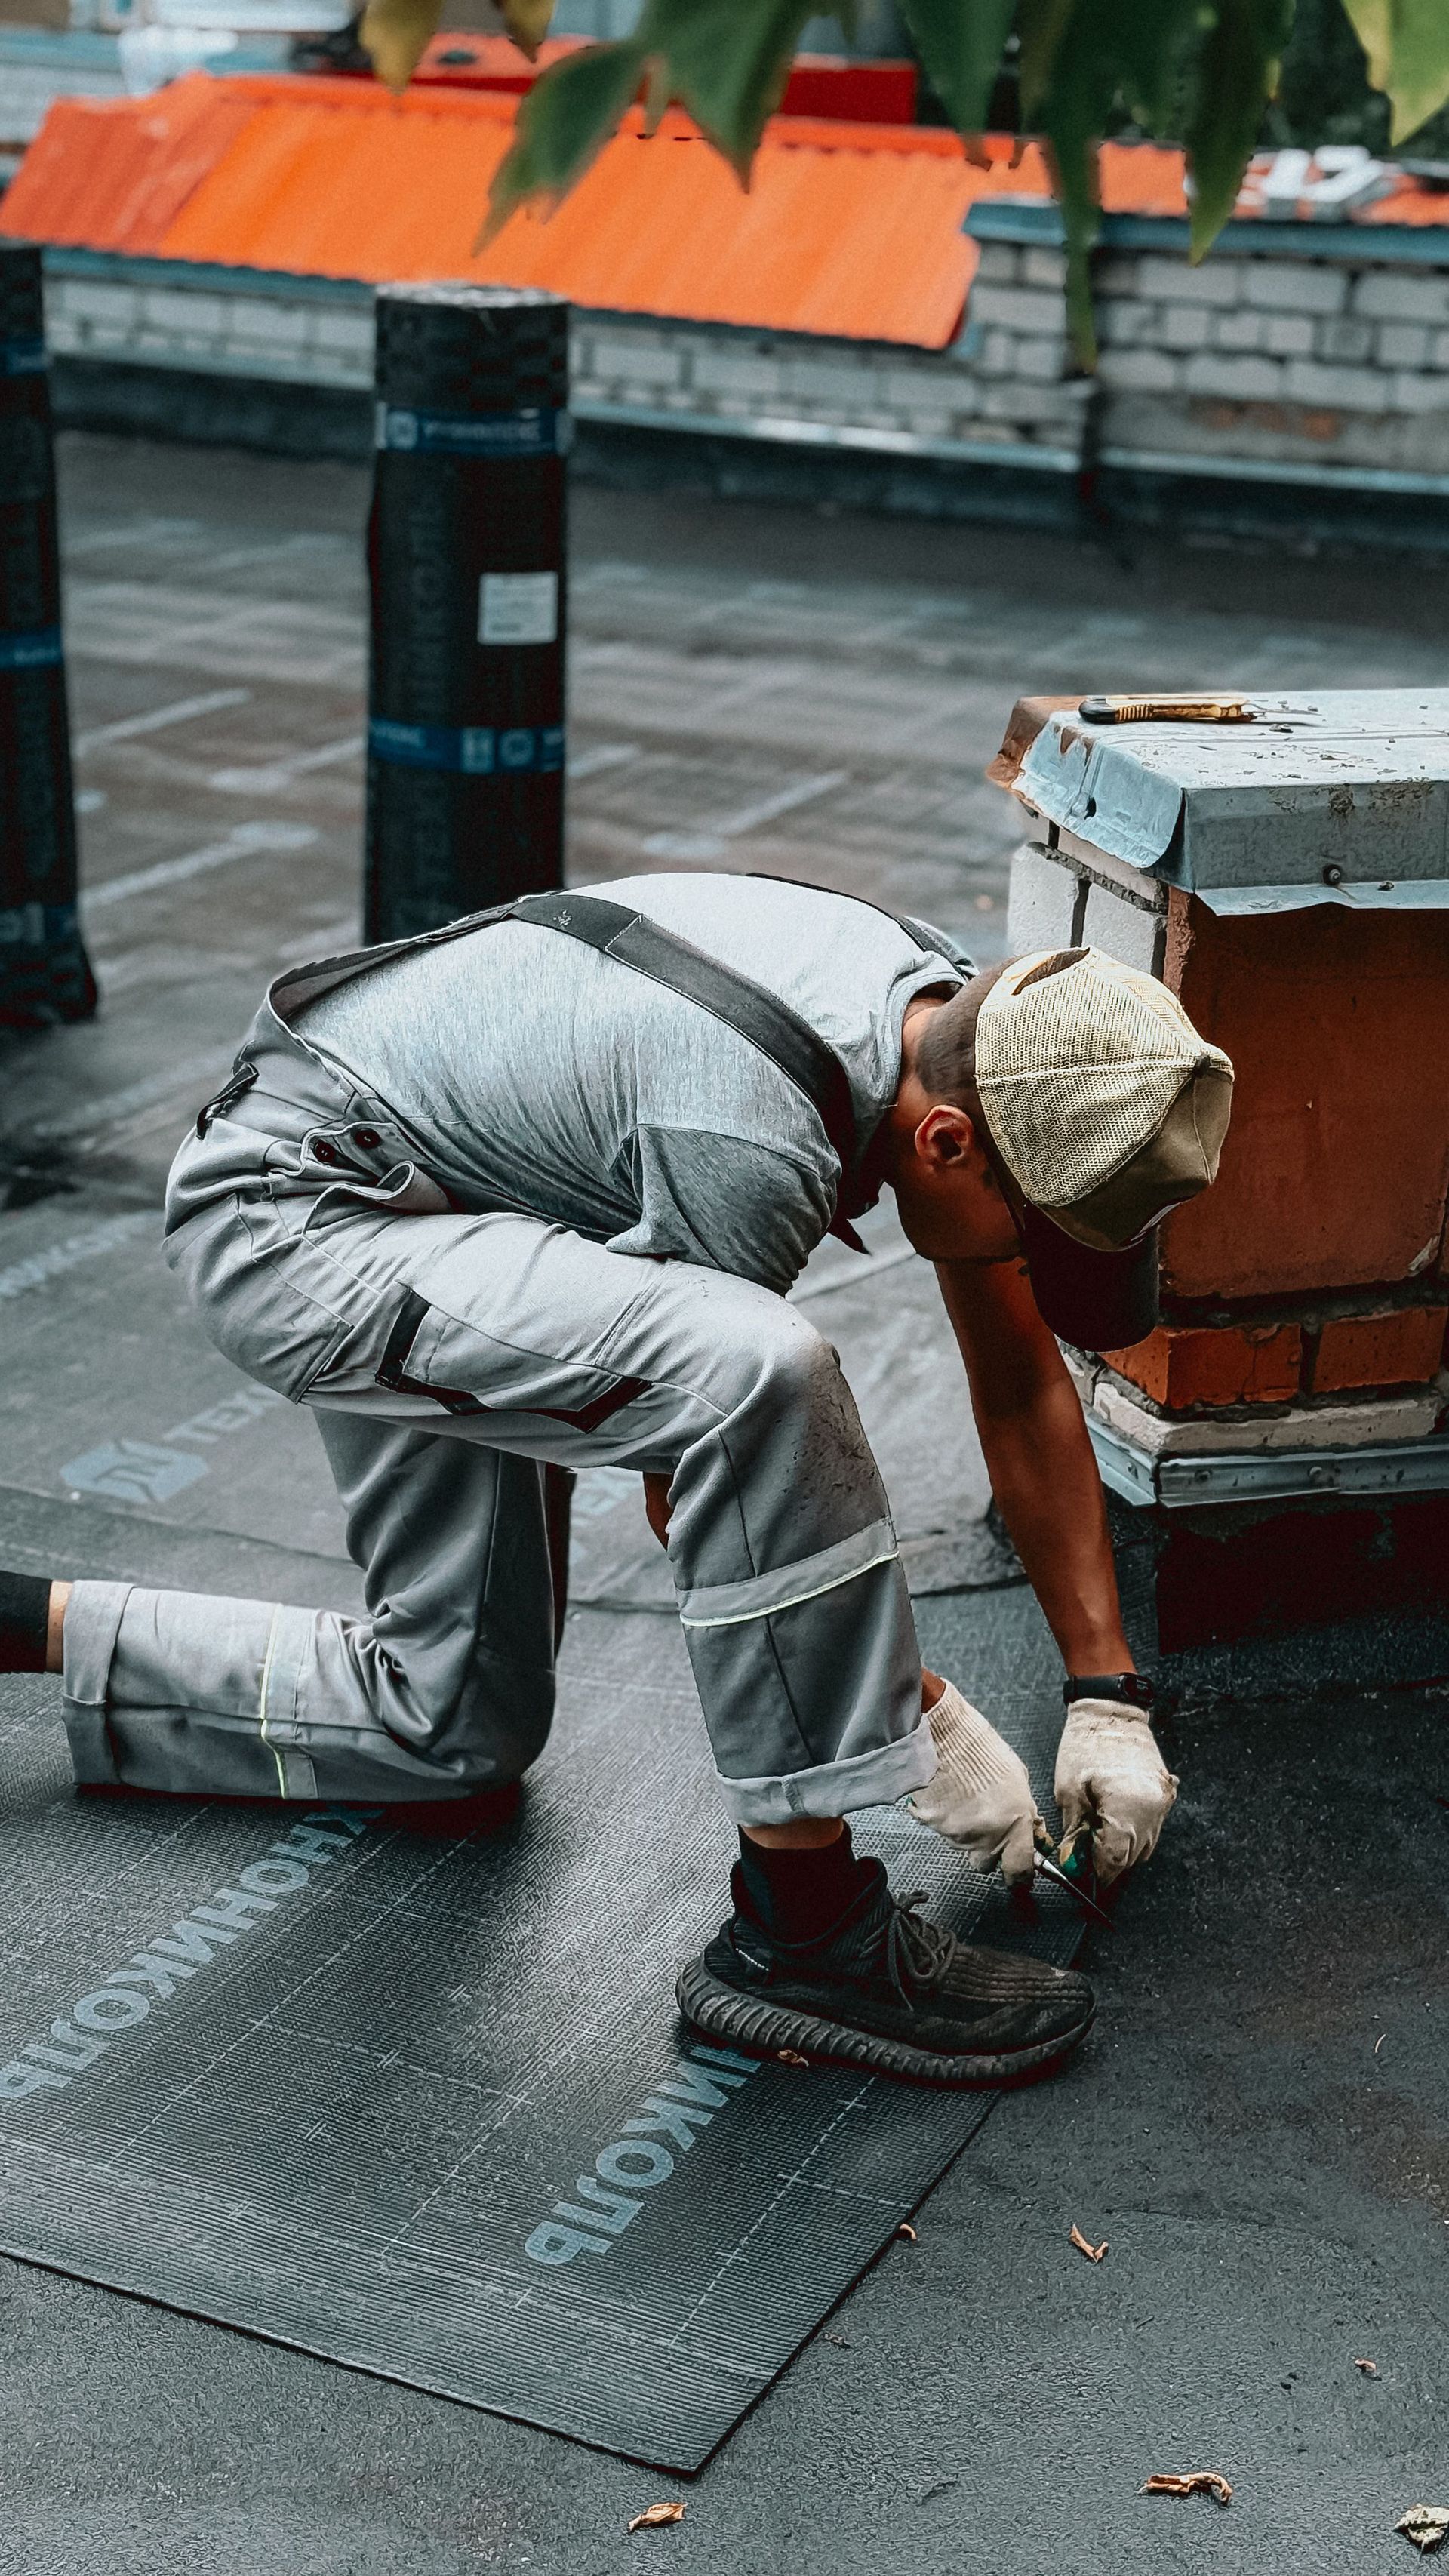
Say a three-crew roofing company in Denton County spends most of the year on residential reroofs. Then it takes on a two-story commercial flat-roof job and a run of hail repairs after a spring storm. At renewal the underwriter asks for the tallest roof the crews worked, how much of the work was commercial, how many subcontracted crews ran under the company name and whether anyone used a torch or other hot work.
Roofing is generally rated as its own higher-hazard class on a general liability application, so the answers to those questions often set both the price and the fine print. Many standard markets decline roofers or cap what they will cover, which is why roofing companies often end up with specialty or excess and surplus carriers. A reroof can also come back to haunt you years later, so it helps to understand what completed operations coverage does after the job is done
before you sign anything.
Why roofing is its own class on the application
Falls, fire from hot work and water getting into a building are the claims that roofers produce, and underwriters price for them. Because the class is treated as higher risk, a policy may arrive with endorsements (written changes to the base form) that narrow what it will pay. Reading those endorsements is just as important as comparing the limits on the front page.
Specialty carriers often write this class, and their forms can differ quite a bit from a standard contractor policy. Two quotes that look alike on the declarations page can behave very differently once a claim lands. Ask for the actual endorsements, not just a summary, and confirm anything unclear with your agent.
Residential, commercial and the height question
Many roofing policies carry a height limitation endorsement, which generally means no coverage for work above a set number of stories. Others are written for residential work only or commercial work only. A company that mostly does single-story homes and then picks up a two-story commercial job may be working outside what its policy contemplates.
That is why the underwriter asks about maximum height and the commercial split. Be honest about both, and if a bigger job is coming, talk to your agent before the first ladder goes up. Adjusting a policy ahead of time is usually far easier than explaining a denied claim afterward.
Storm season work and the out-of-area crew
After a hailstorm, work can pile up fast and crews may travel well outside their usual territory. A policy that names a stated territory may not respond the way you expect when the job sits outside it. Working under another contractor's name or license can also leave a gap, because the policy generally protects the named insured doing the work listed on the application.
Disclose storm work honestly, including how much of it you expect and where. An underwriter who knows about it up front can price it properly or add the right wording, and that beats a coverage dispute after a claim.
Subcontractors and the certificates you collect
Many roofers bring in subcontracted crews during busy stretches. If a sub does not carry its own insurance, the cost of that work can be charged back to you, and it can expose you to claims, which is the situation we walk through in
how an uninsured subcontractor shows up on your audit. The audit looks at who worked under your policy, not just who is on your payroll.
The fix is paperwork. Collect a certificate of insurance from every sub before they start, and where your contracts require it, ask to be named as an additional insured. Keep the certificates current, since a certificate from last year does not prove anything about this job.
Leaks that show up after the job is finished
A roof that leaks two winters from now is generally a completed operations claim, meaning damage that happens after the work is done and the crew has left. Residential roofers in particular sometimes see exclusions or limitations on this coverage, so read the form rather than assuming it is there. Ask whether the policy covers work you finished before the policy started, and what happens to that coverage if you switch carriers.
There is also a risk during the job itself. Many roofing policies exclude interior water damage during tear-off unless the roof was properly tarped or protected. A forecast that changes mid-afternoon can turn a covered job into an excluded one, so crews need a firm habit of drying in the roof before they leave. Keep photos of the tarping on every open roof at the end of the day, because they show what was done if a storm hits overnight.
Workers' comp and the crew on the roof
Texas lets most private employers choose whether to carry workers' compensation, but that choice has strings attached. Many general contractors and commercial building owners require roofers to carry it, and roofing is among the classes with the highest comp rates because falls are the leading hazard. Confirm the details with your agent and, for questions about the rules, with the Texas Department of Insurance or the Division of Workers' Compensation.
A written safety program with fall protection helps an underwriter see you as a careful operator. It also helps the crew, which is the point. Ask your agent which written safeguards your carrier wants to see.
What to have ready before you shop
How long have you been in business? Years of operating history and the owner's roofing experience carry real weight with underwriters.
What is your work mix? Be ready with the split between residential and commercial, plus the maximum number of stories your crews work.
How much do you subcontract? Share what portion of the work goes to subs and how you collect their certificates.
What paperwork backs you up? Bring loss runs (the claims history from prior carriers), your safety program and a few sample contracts.
TAP Insurance Agency is an independent agency that shops multiple markets, so we can line up roofing quotes side by side and point out the height limits and exclusions in each one. When you are ready, you can request a business insurance quote
and we will walk through the application with you.
Call (800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.