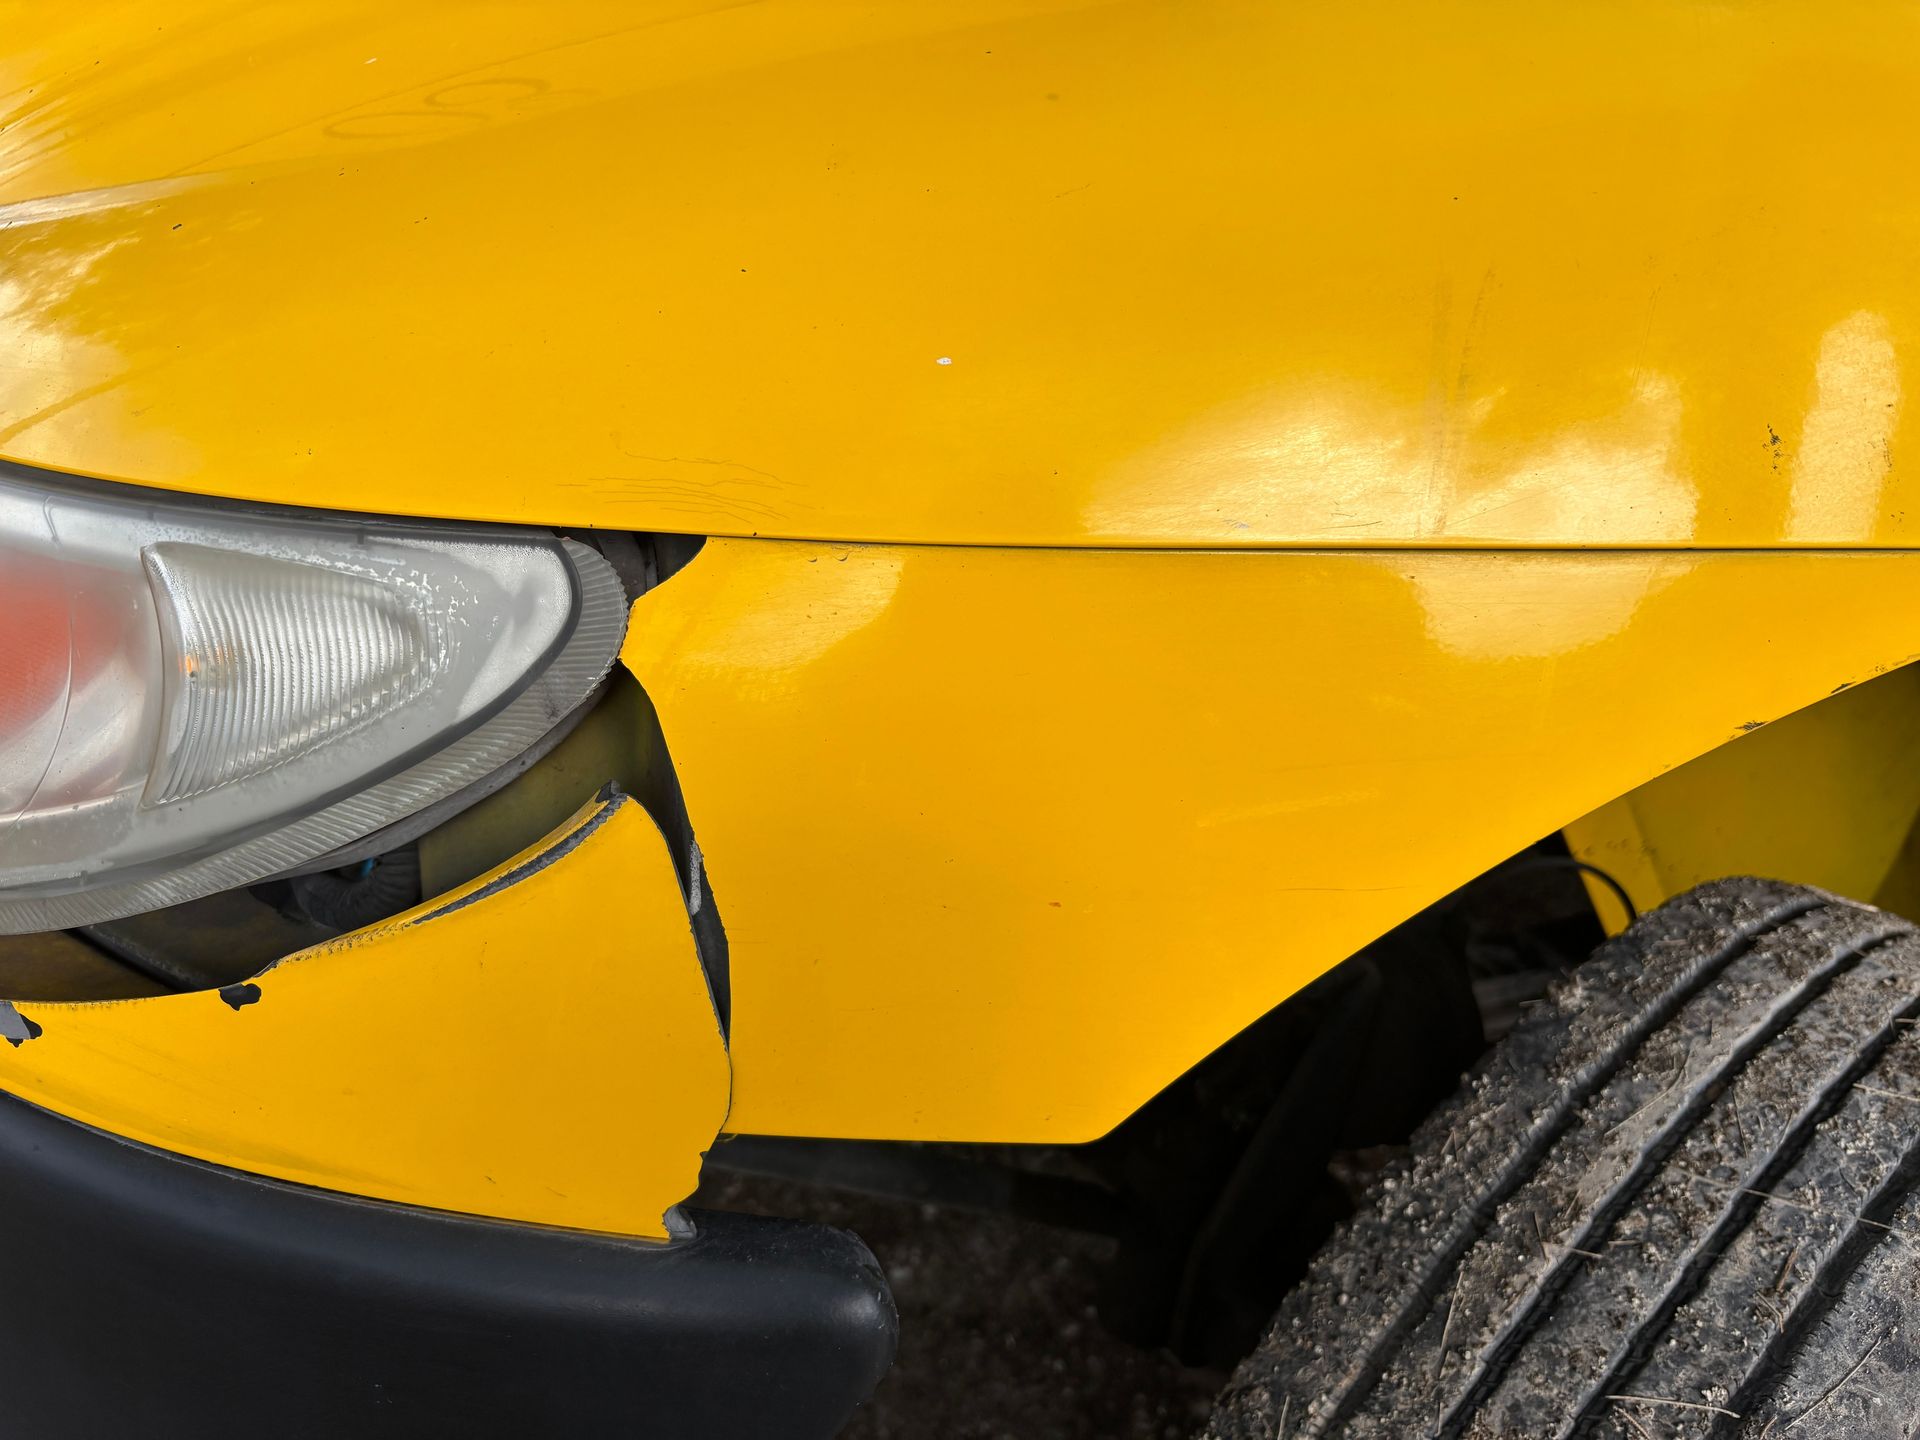
Picture a North Texas family on the first cold night of the season. A dryer vent fire starts in the utility room, the fire department saves most of the house, and the adjuster says the smoke and water damage means about four months of repairs. The family has a place to sleep tonight. What nobody has told them yet is who pays for the next hundred and twenty nights.
The part of a homeowners policy that answers is called additional living expense, also called loss of use and often labeled Coverage D. It pays the increase in your living costs while a covered loss makes your home unfit to live in, up to the limit and time allowed by the policy. It does not pay all of your living costs, only the extra ones, and details vary by policy.
Home fires are a real part of the fall and winter season, and the prevention side is covered in our
home insurance checklist for the heating season. This post covers what happens when prevention fails.
What additional living expense pays, and what it does not
Think of it as the difference between your normal life and your displaced life. A hotel or short-term rental while you still make the mortgage payment, extra mileage when the temporary home is farther from school and work, restaurant meals above your usual grocery bill, laundry, pet boarding and furniture rental are the kinds of costs commonly considered. Whether each one is covered depends on the form.
What it does not pay is anything you would have spent anyway. Your mortgage, property taxes and normal utilities continue, and the policy will not reimburse the grocery bill you already pay. That is why it helps to know what a normal month costs your family before a loss happens.
The standard of comparison is usually comparable housing, not an upgrade. If your family needs four bedrooms to live the way you did before, that is generally the benchmark, and a luxury rental is not.
If part of your property is rented out, such as a garage apartment, the policy may also pay the rent you lose while that space is unusable. That is typically a separate fair rental value provision, not living expense, so ask whether your form includes it.
A word about rentals. Everything here assumes you live in the home. If you rent the house out and a covered loss makes it unlivable, the matching protection on a landlord policy is lost rent instead of living expense, which our post on
loss of rents on a landlord policy walks through. Tenants have a living expense coverage of their own on a renters policy.
Coverage D follows the cause of the loss
Additional living expense only responds when the cause of the damage is a covered peril. A fire, a tornado, hail that opens the roof or a burst pipe in a hard freeze are typically covered causes. A flood is not, because a standard homeowners policy excludes flood, and many flood policies do not pay living expenses at all.
That is worth knowing before the water rises and not after. If you live in a flood-prone area, ask separately what your flood coverage does about temporary housing, and do not assume that the homeowners policy picks up the difference.
The two limits that run out
Coverage D has a dollar limit, commonly set as a percentage of your dwelling coverage, and some policies also cap the number of months. A limit that looks generous on a policy summary can still run short after a major loss.
The time clock matters just as much. Coverage generally runs for the shortest time reasonably needed to repair or replace the home, or for you to settle somewhere else permanently. After hail, wind or tornado outbreaks, contractors are booked, materials arrive late and permits queue up, so a four-month estimate can stretch. If repairs outlast the limit or the time allowed, the extra months fall on you.
When you cannot go home but the house is fine
Some policies also respond when a civil authority, such as a fire marshal or emergency official, bars you from your home because of damage to a neighboring property. That coverage is typically short, often about two weeks, and applies only when a covered peril caused the damage nearby. Evacuations for other reasons may not qualify, so ask how your form handles them.
How to claim it without losing money
Report early. Tell the adjuster on the day of the loss that you will need temporary housing, and ask what the insurer will pay directly and what you will need to front.
Keep every receipt. Hotel folios, rental agreements, restaurant tickets and mileage logs all count. Start a folder or a simple spreadsheet on the first day.
Set a baseline. Write down your normal monthly grocery, gas and utility spending from recent statements, so the extra cost is easy to show.
Ask before you sign a lease. A long rental commitment can outlast the repairs or exceed the limit, so check with the adjuster before you commit.
Ask about an advance. Some insurers will advance part of the Coverage D limit so a family is not carrying weeks of hotel bills on a credit card.
Check your number before you need it
Find Coverage D on your declarations page and write down the dollar limit and any time limit. Then price a furnished rental for your family size in your area, add what a month of restaurant meals above normal groceries would cost, and multiply by the months a major repair could take. If the answer comes up short, ask what it would take to raise the limit.
TAP Insurance Agency is an independent agency, so we can compare how different carriers set Coverage D, and the limit can often be adjusted at renewal or by endorsement, subject to the carrier's rules. When you want a second set of eyes,
ask for a homeowners coverage review and bring your declarations page.
Call
(800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.