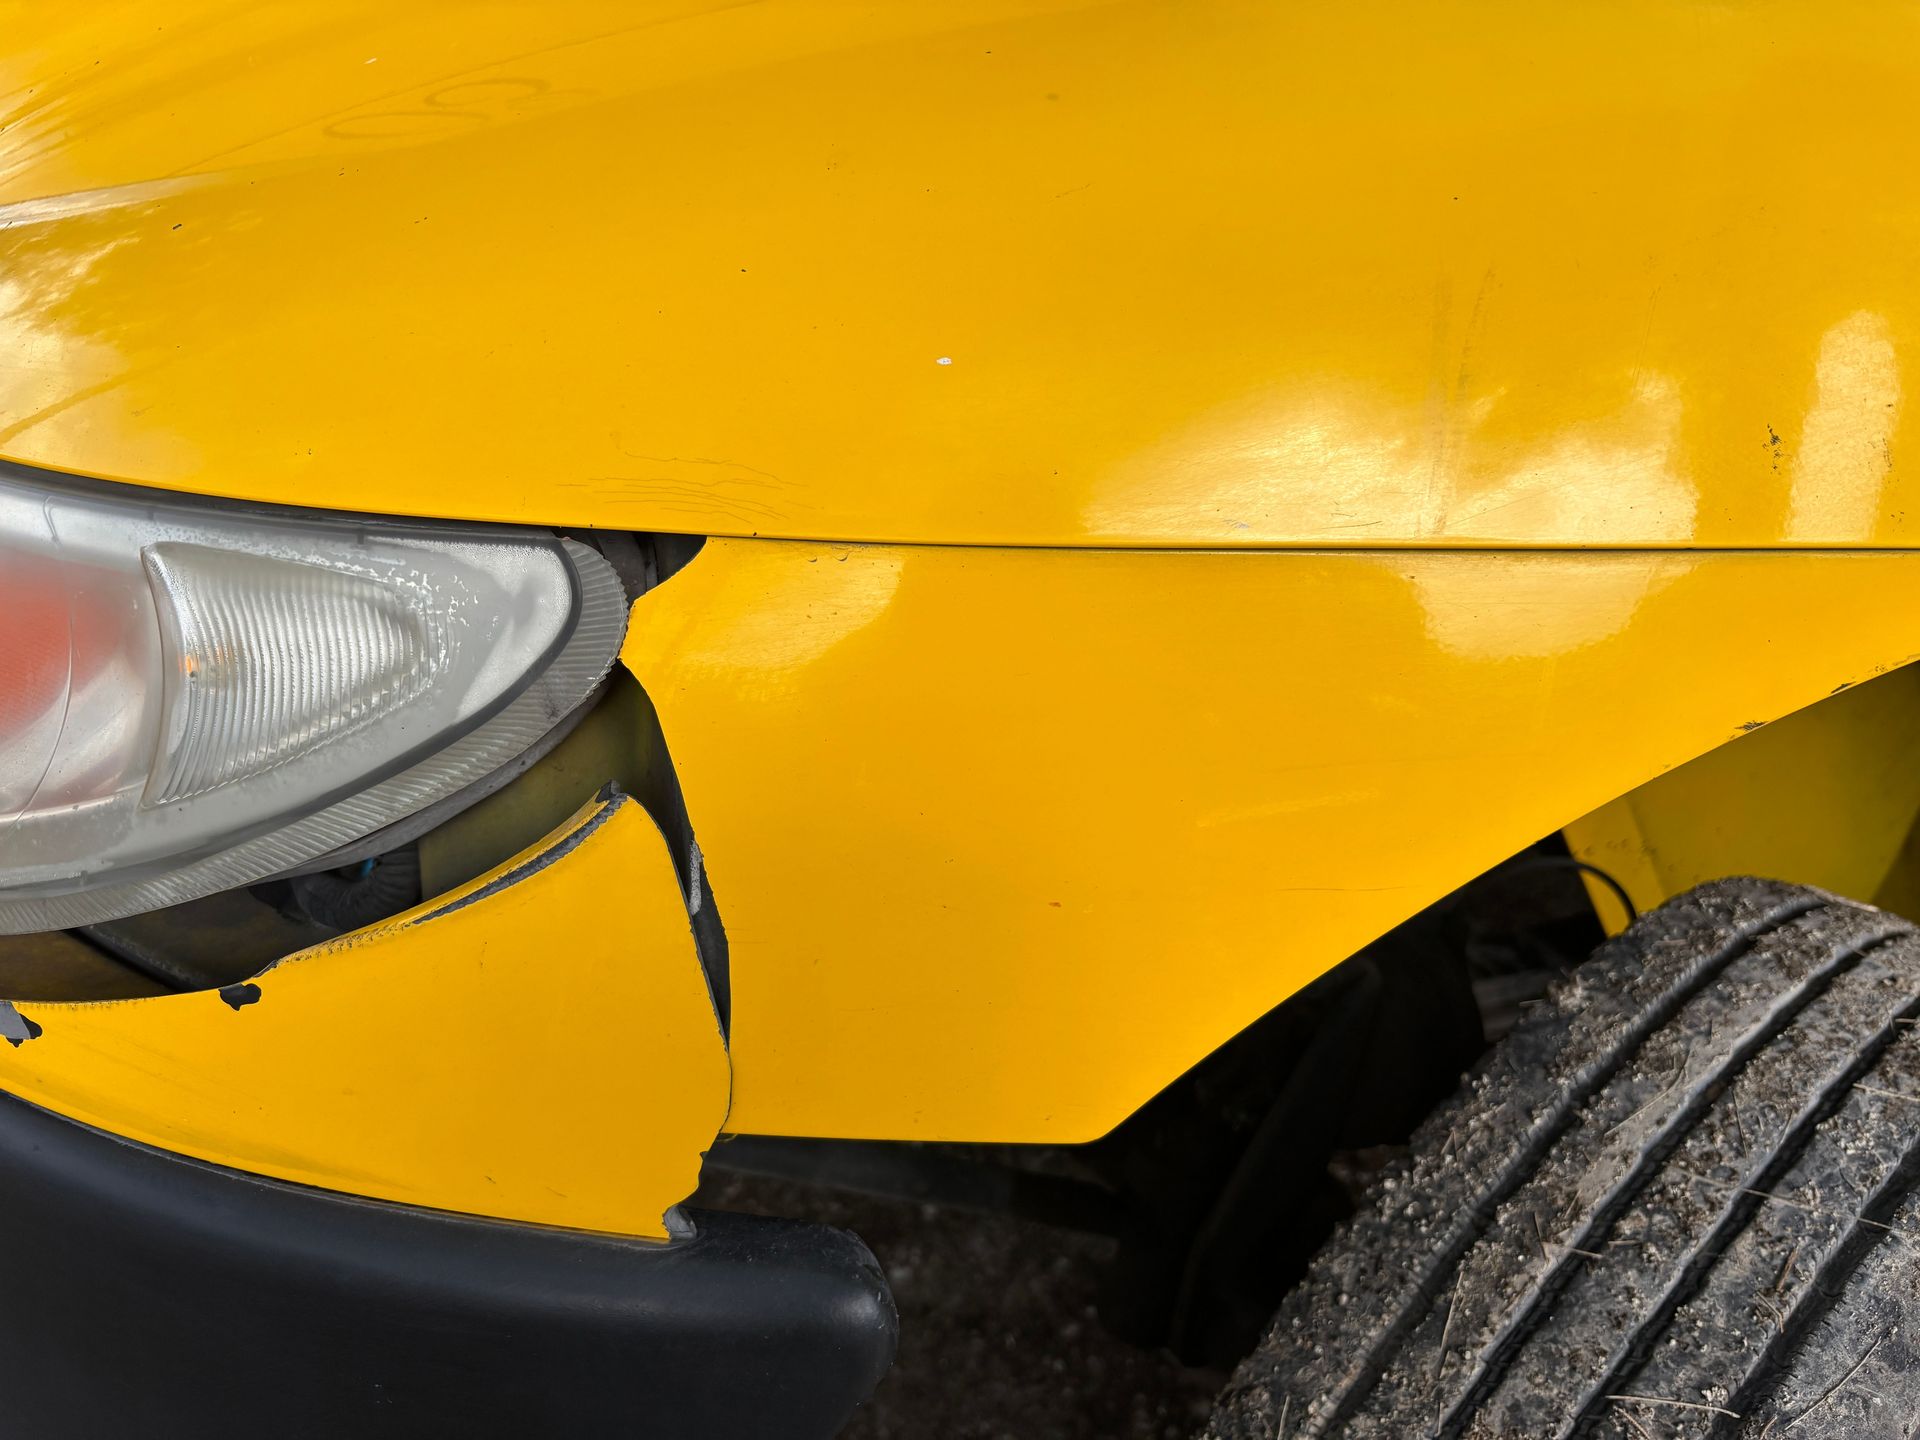
Say a Texas landscaping company with eight employees has flat payroll this year, but its workers' comp renewal comes in noticeably higher. The agent explains that the experience modification factor, or mod, moved from below 1.00 to above it after two crew injuries. The owner has never heard the term and wonders how something that happened more than a year ago is raising this year's price.
An experience mod compares your workers' comp claims with what is expected for businesses with similar class codes and payroll. A mod of 1.00 is average. Above 1.00 means more or costlier claims than expected and a surcharge on your premium, while below 1.00 earns a credit. It does not change the claims themselves, only how your base premium is multiplied. The rules and thresholds are set by the rating bureau and the state, and they vary by situation.
Labor-heavy trades feel the mod most, and our guide to
what a lawn care crew's insurance program needs shows why, since a few injuries can move the number. Here is how it is built, who has one and what you can do about it.
How the number is built
The bureau starts with expected losses, which come from your class codes and your payroll. It then compares them with your actual losses from a window of recent years, typically three policy years and skipping the most recent one. That is why a claim from this fall may not touch your mod for another year or two, and why a claim from three years ago may be about to drop off.
Frequency counts heavily. The first slice of each claim carries full weight in the formula, while the largest claims are partly capped, so several small claims can move your mod more than one large claim of the same total cost. A business with many minor reported injuries can look worse than one with a single serious accident.
Because expected losses come from your class codes and payroll, an incorrect code or payroll split changes the calculation in either direction. Office workers and field crews belong under different codes, and the split needs to match what people actually do.
Who has a mod and who does not
Not every employer has one. A mod generally applies to businesses whose premium is large enough to qualify under the bureau's rules, and it needs a claim history, so a brand-new business starts without one. An employer that has opted out of the system, called a non-subscriber, carries no workers' comp policy to rate at all.
If your business is new or small, you may be rated without a mod for now. That is the best time to build good habits and clean records, since your first mod will be calculated from the years you are living through today.
Read the worksheet, not just the renewal
The bureau publishes a worksheet that lists the claims used, their dates and amounts, the class codes and the resulting factor. Ask your agent for it and check every line against your own records and
the loss runs underwriters read.
Claims that belong to another business, wrong dates, wrong class codes and payroll mistakes are the usual errors. There are time limits on asking for a correction, so do not sit on a surprise.
Where the mod follows you
Premium is only one place the number shows up. Many general contractors, plant owners, public bodies and safety-prequalification platforms ask for your mod, and some set a maximum before they let you bid or step onto their site. A mod that creeps above the cutoff can cost you work long before it costs you much in premium. Subcontractors feel this in particular. A general contractor reviewing ten subs for a job will often start by dropping the ones above its cutoff, so the number acts as a filter before anyone discusses price or schedule.
That makes it worth checking each year, not only when the renewal arrives. If a bid package will ask for it, ask your agent for the current mod and for the next one if it is already published.
What moves the number
Report claims promptly. A late report lets an injury grow, complicates the medical record and can raise the cost. Early reporting and early care tend to keep claims smaller.
Offer light-duty work. A return-to-work plan that brings an injured employee back on modified duty can shorten the claim, and a shorter claim usually means a smaller number in the formula.
Keep claims moving to a close. Open claims are valued with the insurer's reserve, the amount it sets aside for expected costs. If a claim is truly finished, ask the carrier to close it and to review whether its reserve still makes sense.
Ask about a medical network. Texas allows certified health care networks for workers' comp. Ask your carrier whether one is available, since a network can help direct injured workers to doctors who understand return-to-work.
Look for recoveries. If a third party caused the injury, the insurer may be able to recover money from them, and that recovery can lower the cost counted against you. Ask whether it was pursued.
Keep the file accurate. Review the class codes and payroll assigned to each job with your agent and keep payroll records that support them. If the business is bought, merged or split, tell the bureau, because a missed ownership change can leave the mod wrong in either direction.
Safety is the slow lever
None of these steps replaces fewer injuries. Toolbox talks, equipment training, heat and hydration plans for summer crews and a quick review after every incident are the changes that shrink the claims behind the number. Because the mod trails by a year or more, safety work done this winter shows up in a renewal that is still some time away.
TAP Insurance Agency is an independent agency, so we can pull your current mod, review your class codes and shop carriers that handle your trade. When you want a second look, you can
request a workers' comp quote and we will start with your payroll and your claim history.
Call
(800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.