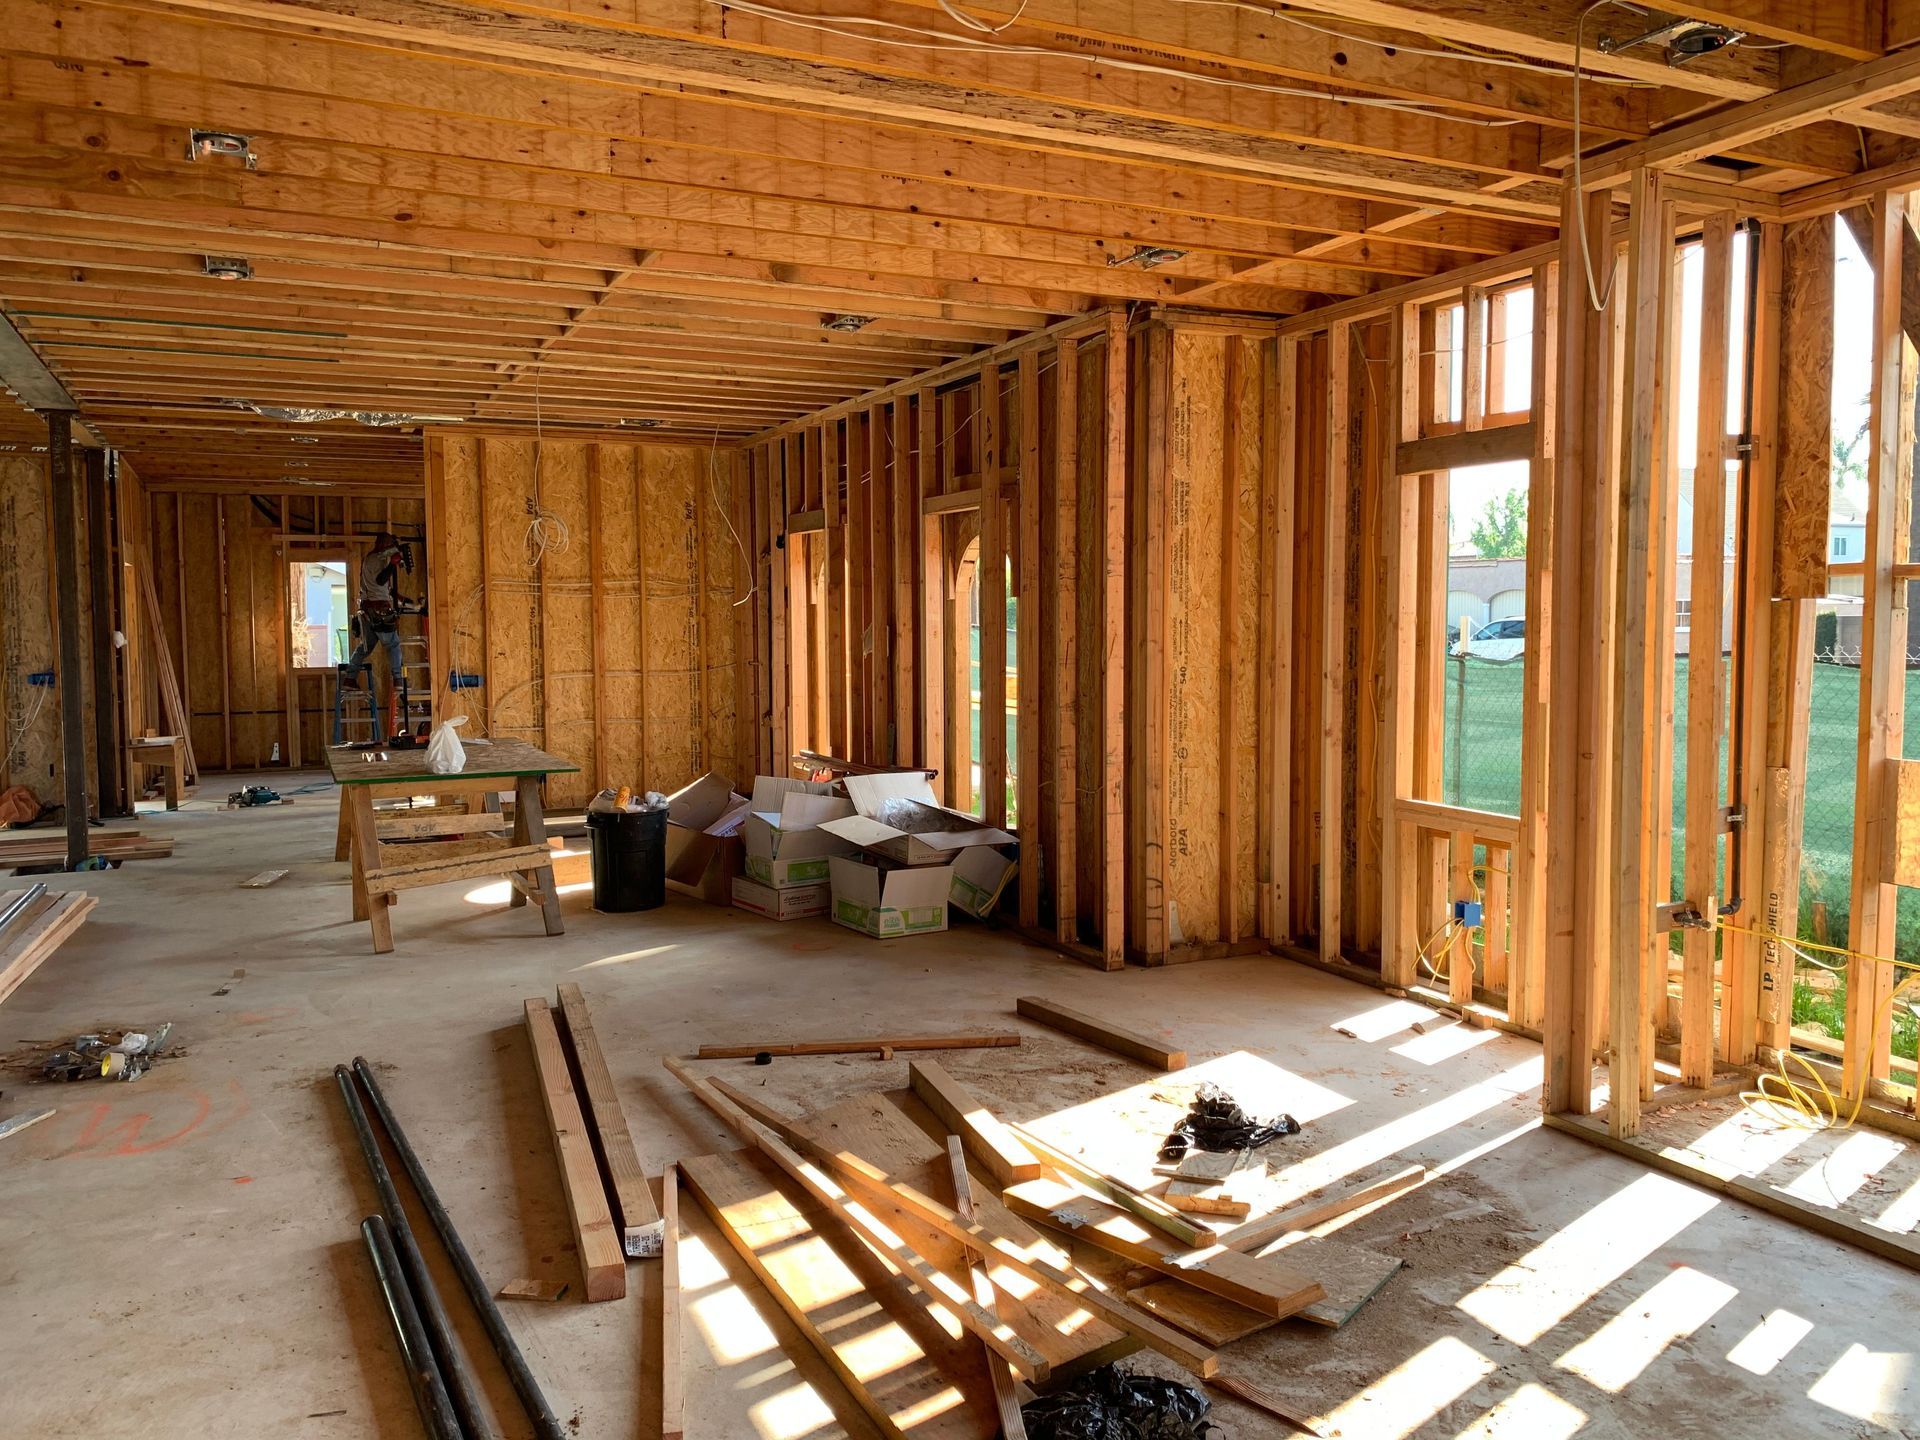
Picture a remodeler in Wise County who hires a framing crew for a kitchen addition. The crew works for three weeks, takes a check, and is never heard from again. Eleven months later the insurance company's auditor calls to review the year. One of the first questions is simple: what did you pay to subcontractors, and where are their certificates of insurance?
The plain answer is that an uninsured subcontractor can be treated as your own exposure. On a general liability or workers' compensation premium audit, payments to a sub with no proof of their own coverage are often charged as if the work were done by your employees or at a higher rate. If the sub is hurt or hurts someone, the claim can also land on you. A certificate collected before the first payment is far cheaper than a gap found at audit.
What a premium audit actually is
Most commercial policies are priced on estimates. General liability is commonly rated on payroll or sales, and workers' comp on payroll by job class. After the term ends, the insurer reviews your real numbers and adjusts the premium up or down. That review is the premium audit, and for contractors it usually includes a close look at what you paid to subcontractors.
Contracts that push requirements down to subs often ask for more than coverage, such as a waiver, and understanding
what a waiver of subrogation commits you to helps you ask for the right thing. The auditor wants records, not explanations. Expect to be asked for payroll reports, 1099s, check registers, invoices from subs and the certificates that go with them. If you can show a sub carried their own coverage on the dates they worked, the payments are often treated more favorably. If you cannot, that payment tends to be rated as your exposure.
How an uninsured sub shows up on the audit
The mechanics vary by carrier and policy, so treat this as general. On workers' comp, payments to uninsured subs for labor are often added to your audited payroll, which raises the premium. On general liability, uninsured subcontracted work can be charged at a higher rate or into a different class than work done by insured subs.
Hiring a day laborer works the same way. If you pay someone cash and have no certificate and no subcontract, an auditor may ask why that person should not be counted as an employee. A written subcontract and a certificate are what turn the payment into a business expense that stands apart from your payroll.
Texas adds a wrinkle, because workers' comp is optional for most private employers. That does not make the subject disappear. General contractors and project owners often require it by contract, public projects have their own rules, and some insurers treat uninsured labor differently. Ask your agent how your own policy handles it before the audit, not during it.
When the sub's missing coverage becomes your claim
The audit is the milder outcome. The sharper one is a claim. If an uninsured sub's worker is injured on your job, that worker may look to the next party up the chain, which can be you. If the sub damages a customer's house and has no liability policy, the customer's attention turns to the contractor who hired the sub.
Your own general liability policy may respond in some of those situations, but it can have conditions about subcontractors, and carriers sometimes ask for proof that you required coverage from the people you hired. A missing certificate does not only cost premium. It can weaken your position when a claim arrives.
Reading a certificate the right way
A certificate of insurance is a one-page summary of coverage. Look at four things: the general liability limits, the workers' comp status or an occupational accident policy, the additional insured wording if your contract asks for it, and the policy dates. A certificate shows coverage on the day it was issued. It does not promise the policy stays in force, so a certificate from March does not prove coverage in October.
Contracts often go further than a certificate. A waiver is a commitment about who can recover from whom after a loss, and a certificate alone does not create one, since only an endorsement on the policy does.
Also watch for the sub who sends a certificate with the wrong named insured, a lapsed date or limits far below your job's needs. Where your own contract passes high limits down the line, the sub may need to carry them too, and the discussion of
excess liability limits contractors are asked for shows how those requirements stack.
A simple routine for hiring subs
Certificate before the first check. No certificate, no payment, no exceptions. A one-page form takes a sub's agent a few minutes, and a legitimate sub will send it.
Written subcontract. Describe the work, the dates, the price and the insurance you require, and have the sub sign it. A handshake does not help at audit.
Calendar the expiration. Put each sub's policy end date on a shared calendar and ask for the renewal certificate before it passes. Treat a lapse as a stop-work item until it is fixed.
Keep the file. Store the contract, the certificates, the invoices and proof of payment together by job. When the auditor calls, you can answer in an afternoon instead of a month.
Where to start
Most contractors do not go looking for this until the audit letter arrives, and by then the sub is long gone. Start with the next sub you hire. Then pull last year's subs and see which ones you can document, because that is the list the auditor will build for you.
TAP Insurance Agency is an independent agency that shops multiple carriers, so we can look at how your general liability and workers' comp or alternative coverage treat subcontractors. Sit down and
talk to a Wise County agent about your subs, and bring a recent audit if you have one. Availability and audit treatment vary by carrier, and we do not give legal advice, but we can explain it in plain English.
Call
(800) 666-2254 — or text
QUOTE to
(817) 646-6700 · tapinsuretx.com
Educational only; coverages and availability vary by carrier. TAP Insurance Agency, PLLC — Rhome, TX, licensed in Texas and Oklahoma.