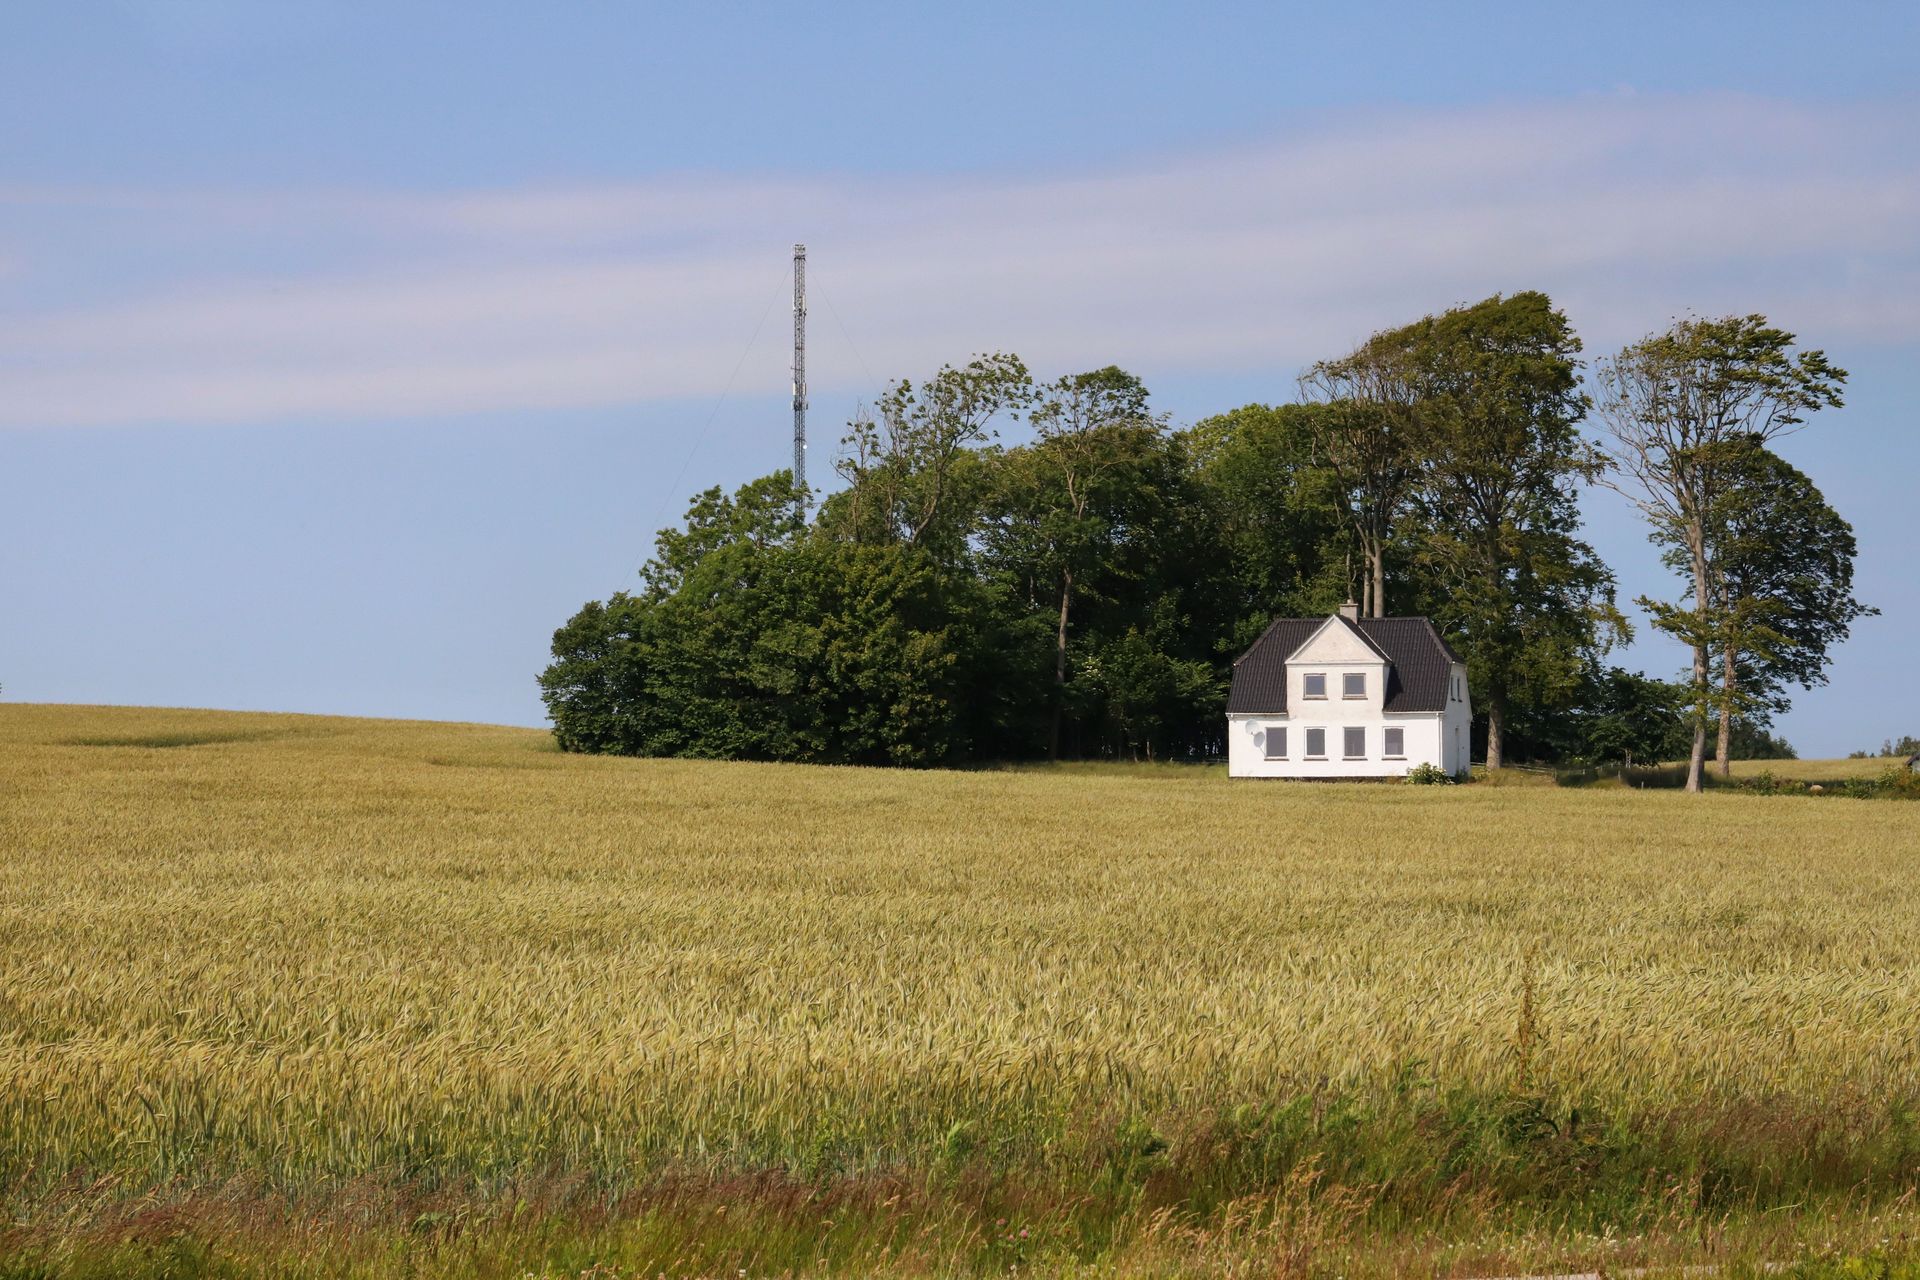
Parker County sits in an unusual spot for insurance purposes: it's growing fast enough that national carriers treat parts of it like suburban Fort Worth, while large stretches of it are still genuine ranch and acreage country with wells, septic systems, long private roads, and working livestock. That mismatch is exactly where coverage gaps show up — a standard homeowners policy built for a subdivision doesn't always fit a property with a barn, a pond, and a half-mile gravel driveway, even if the house itself looks similar to a suburban home.
Why Weatherford, Aledo, and Springtown each need a slightly different look
Weatherford, the county seat, is a study in contrasts — established multi-generation ranch families alongside a steady wave of new rooftops as Fort Worth's growth pushes west. A property that's been in a family for decades often still carries an older homeowners policy that was never updated when a barn, a second structure, or a few head of livestock got added over the years. New arrivals, meanwhile, sometimes buy acreage expecting a standard suburban policy to just work — and find out otherwise at claim time.
Aledo is squarely in the high-growth zone, where suburb meets ranch. Newer construction on larger lots is common here, and it's easy to assume a newer home means a simpler insurance picture. In practice, larger lots often come with outbuildings, fencing, and sometimes a horse or two that a standard policy doesn't anticipate.
Springtown, further out, stays more agricultural and rural in character. Fire department response times, well and septic systems, and unpaved or private roads are all more common here — all factors that affect how a property should actually be insured, and sometimes what it costs to insure, differently than a similar-looking home closer to town.
What a standard homeowners policy tends to miss on acreage
A few gaps show up over and over on Parker County properties, regardless of which town they're closest to:
- Outbuildings and barns. A standard HO-3 policy often provides only a small percentage of the dwelling coverage limit for detached structures — frequently not enough to rebuild a real barn or equipment shed.
- Well and septic systems. These aren't always automatically included at full replacement cost the way municipal water/sewer connections are assumed to be.
- Fencing. Miles of perimeter and cross-fencing represent real replacement cost that's easy to under-insure.
- Livestock and animal liability. Cattle, horses, and other animals create liability exposure most residential policies exclude or cap low (see our related piece on
equine and horse property insurance if horses are part of the picture).
- Private/unmaintained roads. Longer response times for fire and emergency services can affect both risk and how a carrier rates the property.
The fix in most cases is either a proper farm & ranch policy instead of a standard homeowners policy, or the right set of endorsements added to an existing policy — not a wholesale change in carrier, just a more accurate match between the coverage and how the property is actually used.
Manufactured and site-built homes both need a second look
Parker County has a real mix of site-built ranch homes and manufactured/mobile homes on larger lots, especially further from Weatherford's core. If that's your situation, it's worth reading our guide on
manufactured and mobile home insurance in Texas alongside this one — the two sets of gaps (acreage-related and manufactured-home-related) often overlap on the same property.
If your land is leased for hunting
A fair number of Parker County ranch and acreage properties supplement income with a hunting lease during deer season. If that's part of your property, make sure your coverage actually accounts for it — see our companion piece on
hunting lease liability insurance in Texas for what the state's recreational use statute does and doesn't protect you from.
The takeaway for Parker County landowners
None of this means Parker County acreage is hard to insure — it usually isn't, and there are strong farm & ranch markets that price rural Texas property well. It just means the policy needs to be built around how the property is actually used, not assumed from the outside. A five-minute conversation about your outbuildings, water source, livestock, road access, and any lease arrangements is usually enough to spot the gaps before they matter.
TAP Insurance Agency is an independent agency, which means we're not limited to one carrier's underwriting rules for rural property — we can shop your Parker County home or ranch across multiple markets built for exactly this kind of coverage, whether you're in
Weatherford,
Aledo,
Springtown, or anywhere in between.
Hail, wind, and the western edge of the metroplex
Parker County sits squarely in North Texas hail country, and carriers price and structure policies accordingly. On acreage properties the roof conversation gets bigger, not smaller: it is not just the house, but the barn, the shop, the well house and every other structure with a roof on it. Pay attention to how each policy treats roof settlement — replacement cost versus a depreciated schedule — and to the wind and hail deductible, which on many Texas policies is set as a percentage of the dwelling limit rather than a flat dollar amount.
Sometimes the difference between two similar-looking quotes is entirely in those two provisions.
What to have ready when you call
Five minutes of preparation makes the quote sharper: your total acreage and how it is used, a list of outbuildings with rough sizes and what is stored in them, your water source and septic setup, the distance to the nearest responding fire department, a livestock headcount if any, and whether any part of the land produces income — a hunting lease, a hay cut, boarded horses. None of it needs to be exact, and every one of those answers moves the coverage design.
Call
(800) 666-2254 for a free quote, or text
QUOTE to
(817) 646-6700. Learn more at
tapinsuretx.com.
TAP Insurance Agency, PLLC — Licensed in Texas and Oklahoma.